All Quieter on the Middle East Front
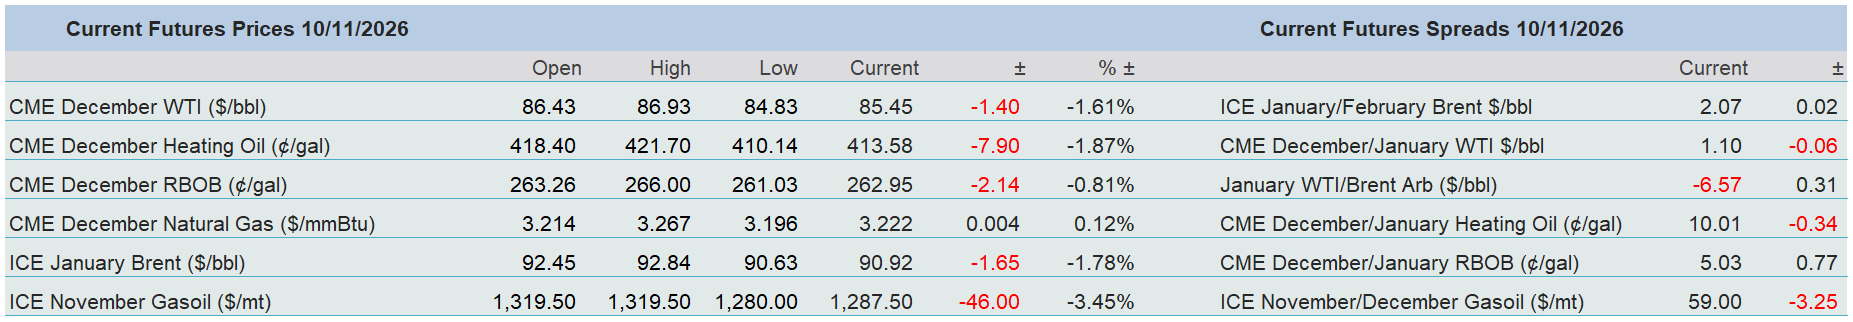
The market is never wrong and the broad-based sell off in oil prices sees long liquidation, relief from inflation strategies and more courage to reflect the current mini glut seen in physical markets. There is also a return to the humbled, as in it never turned up, off ramp for the US President. Two-days of saying that there does not seem to be any need to attack Iran at present gives a gallop to the minds of folk who tend to leap way too early at conclusion. With a US brokered peace chance between Russia and Ukraine adding to bearish conviction, the market is taking to shooting bullish ducks in a barrel. The reset and rethink almost mimics the recent correction seen in the A.I. trade, and like the tech situation, the bullish drivers might have quietened, but they have yet to disappear. Whatever deals being crafted by Qatar, Pakistan and Saudi Arabia, an obstinate Iran is still not in the market for compromise. Iran’s Foreign Ministry spokesman Esmaeil Baghaei said in a briefing, “Tehran will only sign and implement an agreement that fully secures the national interests and legal rights of the Iranian nation.” This thing is much more likely to work itself into a standoff rather than a settlement.
Saudi will no longer foot the bill
Piecing together the moving parts of the Middle East story and putting it into a cohesive oil narrative is nigh on impossible. The whole affair is made up of vignettes ranging from contested borders to price competition, historical peeves and at present a war sporting a standoff that has no end in sight. Therefore, most issues must be viewed in isolation and whichever protagonist a gaze falls upon, know that any attitude will be a parochial one.
Saudi Arabia is arguably the most powerful nation in the area. This is a presumptuous sweep and forgoes a side-by-side reckoning of GDP or military capability with its peers, but for the purpose of this scoping, leeway in assumption is asked for. Having been the de facto leader of OPEC, corralling the cats of its cartel members into mewing in some sort of assembled accord has been nothing less than extraordinary. Assuming the role of swing producer, Riyadh has presided over tightening and loosening production quotas that is akin to the hawkish and dovish practices of any central bank. There have always been gaps in what quotas are officially granted to OPEC members and how much oil is actually produced, but the cheating practices of Iraq, and the associate members of Kazakhstan and Russia, have seen Saudia Arabia pick up the mantle of mediator and often adjusted its own production accordingly and at the expense of its own petrodollar income. Its spare oil capacity, and favourable status as a reliable trading ally along with its ability to have a foot in both camps of geopolitical intrigue that are the Middle East and the West has brought it great favour across the globe. Such was the backslapping between Donald Trump and Saudi Crown Prince Mohammed bin Salman (MBS), last year, the US President told on how he was upgrading ties with Saudi Arabia, designating the Kingdom as a major non-NATO US ally.
Odd then that such a public declaration of allyship did not come with the courtesy of consultation. This of course refers to how the United States launched the war against Iran in 2026 without discussing it with Saudi Arabia or its other Gulf partners. MBS must now be choking on the finery of securing a higher geopolitical kinship with Trump, the aftereffects of this ill-planned war has caused immeasurable hurt to the prince’s Kingdom. The last effective proxy of Iran, the Houthi rebels of Yemen, have been a thorn in the side of Saudi for some years, but after this current war started, they have become emboldened and successful. The stirring up of the Houthi hornets’ nest might be laid down at how Saudi, back in January, told Iran that the Kingdom would not allow its airspace or territory to be used for any military attack on Iran. Notwithstanding having to experience drone and missile attacks from Iran, Saudi has been for months faced with a pinched Hormuz on one side of its geography hampering oil exports and a similar situation in the Red Sea on the other. Nifty ship-to-ship transfers, running tankers dark and offering discounted crudes into the European market have meant exports are freely flowing, all be they cheap. Indeed, last week the official selling price (OSP) of Saudi Light grade into Asia was reduced by $2/barrel. It is gaining ground in the all-important Chinese market, and as seen on Reuters, Kpler and Vortexa both recorded a surge in imports from Saudi Arabia, putting October arrivals at 1.6mbpd and 2mbpd, respectively. China’s official data showed imports from Saudi Arabia averaged 1.62 million bpd in 2025.
The monthly OPEC meetings of late we suggest are window dressing. The rubber stamping of keeping quotas as is, likely stems from the inability for any Gulf nation to increase exports into a bottleneck and belies an undercurrent of competitiveness to attain greater market share. The nettle has already been grasped by the United Arab Emirates. Before it left OPEC on May 1st, 2026, it harboured greater autonomy from OPEC and for years expressed a desire to flex its spare capacity muscles. The Iranian war was a gift for Abu Dhabi and perfect cover for it to finally achieve what has been signalling and broke asunder its cartel obligations. This is much to the chagrin of its once great ally, Saudi, whose nose is now twitching from the likes of Iraq, Kuwait and even Libya all making noises on wanting to increase oil production. The oil market well knows of the potential gush of oil building up from the producers of the Persian Gulf, which is why any sort of agreement to end the war however far-fetched, and given the backdrop of the US Midterms and a current conciliatory Donald Trump, will keep prices tamed for a while. With the demand destructing state of freight rates causing geographical nearby gluts, securing custom for the future is vital for any oil producer. Which in the end is what Saudi is and what Saudi does, and with this war accelerating deglobalisation and national self-interest, one can hardly see Riyadh opting to sacrifice any more of its capability given the hurt it has endured so outlined above.
Overnight Pricing
10 Nov 2026
