All Roads Lead to the White House. And to Persia. And to Ukraine.
This is the place where the previous month’s happenings are summed up, and conclusions are drawn about what they might mean for the immediate future. Notwithstanding the usual turbulence observed in September, the first part is comparatively easy. The second part is not. Indiscriminately or subjectively choosing the major factors that shaped the mood of consumers, investors, and central bankers, they were the geopolitical hotspots, elevated anxiety about rising consumer prices, the resultant rout in bond markets and increase in borrowing costs, and, finally, the somewhat confusing picture of whether oil supply, both crude oil and refined products, is now sufficient or not.
In any case, the price of any asset class is almost exclusively influenced by the price of energy and expectations about the direction in which it might move. The economy, in general, is in semi-decent shape. The optimism chiefly originates from the tech sector. Major stock indices failed to make significant advances last month, but the Nasdaq Composite Index gained almost 2%. The rest struggled.
Historically expensive energy has had, and plausibly will have, an adverse impact on consumer prices, even though the US PCE Price Index, the Fed’s preferred measure of inflation, came in below expectations for August. Without being a scaremonger, there are two points that need to be made about the relatively auspicious reading. The first is that the US Bureau of Economic Analysis’s revised methodology for calculating the PCE Price Index came into effect on Wednesday and was applied retroactively to 2021. Second, the better-than-forecast data, although at 3.4% still above the 2% target, is juxtaposed with consumer spending, which showed a surprise jump in August.
So, is inflation a concern or not? Are consumers suffering from an ‘affordability crisis’? Not exactly science, but the chart the co-author of this note shared speaks volumes. It shows a 32% rise in the 10-year US bond yield since March and a 32% drop in McDonald’s stock over the same period.
Central banks appear to agree with his comment on this inverse relationship: “If that doesn't show how yields hurt the ordinary man, I don't know what does.” The US and several other European governments now have to pay interest on borrowing money and financing widening fiscal deficits at levels not seen for more than 20 years. The ECB, the BoJ, the Fed, the Norges Bank and the RBA all increased their benchmark lending rates in September. Despite the unexpectedly welcome PCE reading, further hikes cannot be ruled out, as inflationary pressure is clearly persistent.
Inflation and inflation expectations are reflected in rising bond yields, and they are, in turn, influenced by energy prices. Logic then dictates that the sooner energy prices fall, the sooner inflationary pressure eases. The signs in this respect, however, are ominous. There was a genuine scare in the first half of September that the situation in the Middle East could get out of hand. Not only were hopes of a de-escalation of the Persian Gulf conflict relegated to the level of daydreaming, but the war also expanded to the Red Sea as Iranian proxies, the Houthi rebels, attacked the Saudi pipeline, which circumvents Hormuz, and announced a blockade on Saudi shipments through the other vital chokepoint, the Bab el-Mandeb Strait. In the process, the US spectacularly turned its back on its most crucial regional ally, refusing to heed the Saudi call for help in retaliating against the Houthis. The situation has normalised over the last two weeks, and Middle Eastern crude oil exports have reportedly undergone significant improvements, although the extent of this is open to debate.
While the apparent rise in crude oil availability led to occasional weakness in oil prices, the floor was firmly in place due to general product tightness and, in particular, diesel shortages. It seems the Administration is in panic mode about how to mitigate the impact of the scarce global availability of this pivotal trucking and agricultural fuel, just a month before the midterm elections. An export ban is politically fraught with danger; pressure on Ukraine to halt attacks on Russian refineries has increased, but to no avail, and the release of refined products from European SPRs has, so far, remained at the level of narrative. While a US export ban might not be feasible, Russia and China have no such qualms. As US refinery maintenance season is, at least partially, underway and distillate stocks in major hubs are depleted, product prices are well supported. Both the CME Heating Oil and ICE Gasoil cracks remain historically very high, while RBOB is also stubbornly stable.
If one dares to conclude, the conclusion is an obvious one. Unless a truce, and by that we mean an enforceable and reliable one, is instilled, high energy prices will prevent consumer prices from retreating. Bond yields will remain elevated, and interest rates will keep climbing. And the prospects of reconciliation? We shamefully admit that we have no idea. No doubt, the seeds of demand destruction are being sown, but for now, supply considerations remain the dominant driving force.
Where from here?
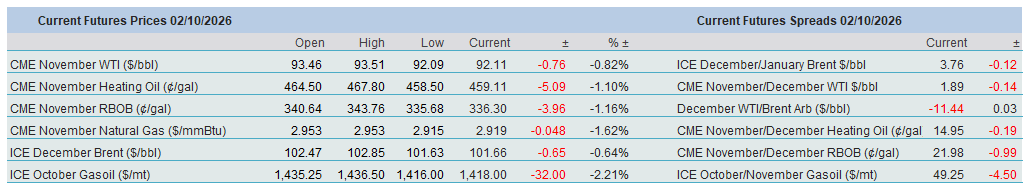
If the last month, the last quarter, and the previous half-year left us in a state of confusion, the new month and the final quarter of 2026 have kicked off much in the same fashion. Heating Oil and Gasoil, the recent trailblazers, were heavily sold off as the US continues to put pressure on its allies to alleviate the diesel outlook—a coercion disguised as a tacit admission that, in this interconnected economy, friends should be leaned on rather than alienated. The role of middle distillates has been taken over by their lighter peers, gasoline and jet fuel. The suspension of Chinese refined-product exports sent gasoline prices sharply higher, while ARA jet-fuel inventories, according to Insight Global, are at their lowest level in six years. Reports by the WSJ that the US is sending its third aircraft carrier to the Middle East supported crude oil, but some pre-weekend profit-taking is reversing the trend observed yesterday.
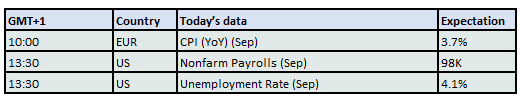
All the while, the US job market remains solid (US unemployment rate is to stay stable at 4.1%), and global factory activity is resilient. These are additional ingredients in the inflation cocktail, which will ultimately lead to further rate increases. This is what the global bond market implies, with yields in the US and Europe climbing further yesterday. Under the US-induced energy crisis, consumers, homeowners, borrowers, and government Treasuries all suffer. So, where do we go from here? It is impossible to know. There is too much to ponder and too little to rely upon.
Overnight Pricing
02 Oct 2026
