An Almost Compelling Argument
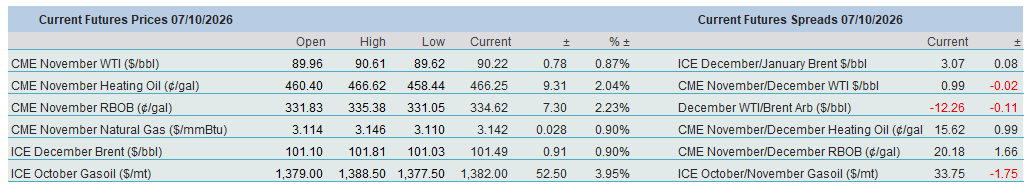
Numbers do not lie. Well, usually they don’t. If you add two to two, you get four. If the price of a medication costing $100 is cut by 600%, the patient will get paid $500 for the prescription. If 5.8 million bbls of crude oil have been pumped through the East-West pipeline, as estimated by Aramco’s CEO, or 12 mbpd of crude oil and 2 mbpd of products are transiting the Middle East, according to the boss of Vitol, the oil balance changes materially. Some estimates suggest that, due to ship-to-ship transfers, Middle East oil exports have reached pre-conflict levels. Another round of SPR releases, this time involving crude oil and diesel, was not lost on the oil fraternity either. The sell-off that began on Monday continued, with the distillates leading the way.
Yet sellers shied away in the mid-afternoon. One reason is a storm approaching the US Gulf Coast, threatening to hinder oil production and refinery operations. Then, there is the geopolitical storms around Iran and Ukraine. Skirmishes between the Yemeni government and Houthi rebels are intensifying, as are attacks on Saudi infrastructure, including airports, 3 years after the despicable attack on Israeli civilians. The war between Ukraine and Russia will likely escalate. The Ukrainian President warned of a massive Russian assault on Ukraine, and we all know what the targets of Ukrainian retaliation will be. Friday’s agreement to release 100 million bbls of crude oil and diesel from the SPR appears as Trumpesque as the Iranian Memorandum of Understanding signed in June and torn up two weeks later. Details will not be worked out until after the middle of next week, the IEA says. Confusion reigns.
Oil executives at the annual Energy Intelligence Forum here in London warn of perilously low global stock levels. The Aramco CEO reckons that 3 billion bbls of oil were lost from the region as a result of the Iranian conflict and that it could take up to two years to replenish depleted inventories. Numbers don’t lie; they show a reassuring increase in oil availability from the Middle East. Sentiment, however, must never be underestimated, and there is presently no conviction that the welcome rise in supply and exports is sustainable.
No Alignment for 4Q, Relief for 2027
Although oil prices, led by distillates, have eroded recently, the EIA, in its updated Short-Term Energy Outlook, still expects a tighter oil balance for the rest of the year. Its view is not aligned with that of the wider market, although adjustments are feasible in a month’s time if oil volumes from the Middle East remain stable. In fact, the EIA has made some inevitable revisions. Both demand and non-DoC supply forecasts were downgraded for the fourth quarter of this year and for every quarter of 2027. These amendments were steeper on the supply side, resulting in higher calls for DoC oil than predicted a month ago.
Last month we touched on the topic of demand erosion. We observed that all three agencies have reduced their global oil demand forecasts for this year since March, as high oil prices have adversely impacted global consumption. This demand deterioration was partly due to government efforts to mitigate the harmful impact of scarce supply and partly to market forces, as high oil prices led to falling consumption.
This trend continued for the whole of 2026 in the updated Short-Term Energy Outlook. In March this year, the EIA predicted global oil demand to stand at 105.17 mbpd, only to downgrade it every single month and to reach 102.42 mbpd seven months later. While supply from producing countries outside the OPEC+ alliance was upgraded by more than 3 mbpd, DoC production, particularly from the Middle East, has been severely reduced. Pre-conflict, it was estimated to be 43.90 mbpd, versus the current projection of 34.84 mbpd.
This significant 9 mbpd decline has had a tangible impact on the global oil balance and on OECD oil inventories. In March, stock builds were pencilled in for every quarter of the year. In October, a global supply deficit was recorded. In March, OECD oil inventories were seen bidding adieu to 2026 at 2.937 billion bbls. The latest prognosis puts it at 2.645 billion bbls. For the October-December period, stock depletion is forecast to continue at the rate of 690,000 bpd. While it is not as robust as the 1.71 mbpd supply shortage projected last month, maybe it is not the point. Maybe the crucial factor is what oil executives at the Energy Intelligence Forum, cited above, emphasised. Global stocks are wearing thin, and the lack of prospects of a substantial stock build in the foreseeable future might just put a floor under the market or might even serve as a base for a price rally.
Defining ‘foreseeable future’ is a tricky exercise in the current vicious trading environment, but if the EIA’s view is anything to go by, next year should bring considerable relief. The growth in combined supply will markedly outpace demand expansion. The world will need around 2.21 mbpd more oil in 2027 than this year, reaching 104.64 mbpd. Non-DoC supply, on the other hand, will expand by 3.79 mbpd and OPEC + will pump 4.65 mbpd more than this year. This implies a year-on-year fall of 1.57 mbpd in DoC call, from 36.17 mbpd to 34.60 mbpd. As the group’s output level is seen at 39.49 mbpd in 2027, global oil inventories will be inflated to the extent of 4.9 mbpd, and OECD stockpiles will swell to a very comfortable level of 3.102 billion bbls, 470 million bbls above the end-206 level.
Numbers might not lie but, they can be revised. It appears absolutely pivotal that the oil flow out of the Middle East will grow, will prove reliable and stable and will be based on a mutually enforceable peace deal between all the parties involved. Otherwise, current forecasts will prove inaccurate, tension will occasionally or frequently flare up, supply will be intermittent, and the risk premium will remain elevated. For one, the EIA is cautiously optimistic. Although they upped their price forecasts for 2026 and 2027, they anticipate softer prices next year, with Brent averaging $84/bbl compared to $96/bbl this year.
Overnight Pricing
07 Oct 2026
