Ballot Blues
No doubt the true nature of the peace overtures currently correcting oil prices will emerge after the US Mid-Term election result is revealed. There will be reams of opinion to sift through, including ours, but predictors of election results we are not and believe rather cynically that US voters are now in the habit of not telling the truth to pollsters. Therefore, and as is with the rest of the world we await the outcome with a guarded attitude. Hindsight is a wonderful thing but applying it here seems somewhat apposite. Prices, particularly that of Brent, had become very stretched and encouraged on by the premiums of expiry. Therefore, when the inevitable technical set back yesterday morning coincided with a market mood more ready to accept the possibility of there being substance to peace talks, and hearing from Iran that the Supreme Leader had given permission for limited negotiations to take place, there seemed a shift in rhetoric. With the US President belting out his favourite top hit of the conflict with Iran close to being over, length had little choice other than to react with bears finding the most fertile environment for a month. Apple results, bond issues finding failure, warning after warning of A.I. troubles and any number of industrial and economic markers be damned, we all just want to know if the ‘Blue Wave’ is true.
Change is perpetual
The pace and change of the world and the technological leaps including those made possible by the advent of A.I. will bring challenges to many types of businesses. To think that such innovations would allow the likes of exchanges to remain unaffected would be foolhardy and while the age of non-touch trading is booming in the mercantile of the world, the strict confines and rules of recognised investment exchanges (RIE) run counter to the modern ethos that almost anything should be tradeable and by whoever has enough risk appetite.
Trading in futures markets is not the remit of retail customers, well, those that have not experienced times on open-outcry trading floors, pre-electronification, or very, very wealthy individuals. There are of course exceptions, particularly participants joined in a covering conglomerate, commonly known as ‘arcades’, which must adhere to the rules of exchanges, the governing compliance body and more importantly the strict profit and loss controls and constant monitoring of risk profiles. In oil futures contracts, for example, there are defined monthly expiries, along with settlement procedures where monies gained or lost are justified through an international clearing system that has taken decades to establish and hone.
Oil futures are for professionals; they are exclusive for a reason because of the incredible underlying risk. This risk is manifold. Price volatility, particularly in contemporary times is obvious enough, but there are other preclusions keeping ordinary Jos and Joes putting on their best ‘Gordon Gecko’ and diving in with a “Blue Horseshoe loves Gasoil.” The price belies the contracts size, one might want to be long Gasoil at say $1400/tonne, but that length comes in a minimum lot size of 100 tonnes. It does not cost $1400 it costs $140,000, and even though this expense is mitigated by only having to fund the required deposit requirement, which eats into any monies deposited against positions, initial margins are subject to change in high volatility periods and become even more expensive as expiry looms. Staying with Gasoil, there are few folks, let alone professional fund managers, who own tankage in Amsterdam-Rotterdam-Antwerp able to make or take delivery if positions are left open into expiry. They have long vacated the scene and sensibly rolled their positions before being subject to either heightened financing or being pin balled by outlandish price fluctuations at the death of each monthly contract.
Yet despite all this weighty resistance, the ‘would-be’ oil trader from Nowheresville, Arkansas or Wellingtonbootshire, England is expressing discontentment at not being able to join in with the perceived fun of Hormuz. Well, that is what we are told by the owners of perpetual markets. Perpetual futures allow for speculative trading on a commodity or asset future price without having to navigate the costly process of monthly expiries and can be held indefinitely. There is no delivery process, ‘perps’ are cash-settled derivative contracts that can be owned as long as a trader maintains enough collateral or margin, not on whether the calendar forces liquidation. There has been a filing of an application with the U.S. Commodity Futures Trading Commission (CFTC) by ‘Kalshi’, the prediction market platform, to launch a non-expiring West Texas Intermediate (WTI) perp, which if ratified will be the first of its type on any US regulated exchange. The application has been challenged by the Commodity Markets Council, a group containing CME Group, NYMEX and ICE Futures US. It questions how a contract relying on daily funding payments can properly stay aligned with the underlying official futures price of WTI; that it could invite volatility, and manipulation and that if it operates offshore, it will avoid the scrutiny of traditional compliance boundaries.
The wider argument, and one that we consider the most valid, is how perps can be viewed as a futures contract at all. They are more akin to a perpetual swap, being funded against an underlying contract rather than priced against its own value. Oil futures contracts converge toward physical market delivery prices as they approach expiration, perps are a synthetic contract tracking an underlying price, but one wonders where the guard rails or price police might be to stop over exuberance. Yes, there is a funding rate mechanism stopping a propensity to be overly long as a fee need be paid to shorts, a sort of ‘long tax’ if you like, but how punitive that might eventually be is rather obscure.
As it stands, and to be provocatively insulting, it is unclear the difference between oil perps and spread betting. However, the world and its ever-growing population of investment tourists are becoming increasingly sophisticated and the push for trading equality will not go away. We have not heard the last of this and whatever guise and tweaking required ensues for perps, they will return. Only last week ICE announced a deal with Trade[XYZ], a leading innovator of real-world-asset perpetual markets, with the aim to bring an onshore, bespoke contract for retail-focused businesses with all the bells and whistles of compliance and oversight. No doubt the likes of CME and others will follow suit in some way shape or form. If you are of a mind that algorithms, and high frequency trading upsets the natural price of oil, then don’t look now, here come the prodigious proletariat and their dialled-up trading enthusiasm.
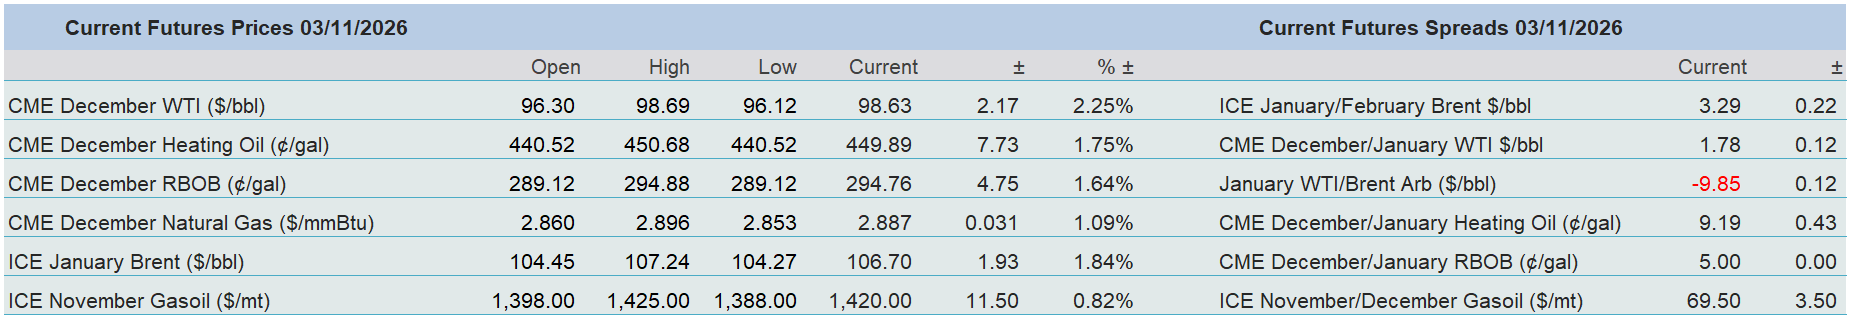
Overnight Pricing
03 Nov 2026
