Bonkers Day
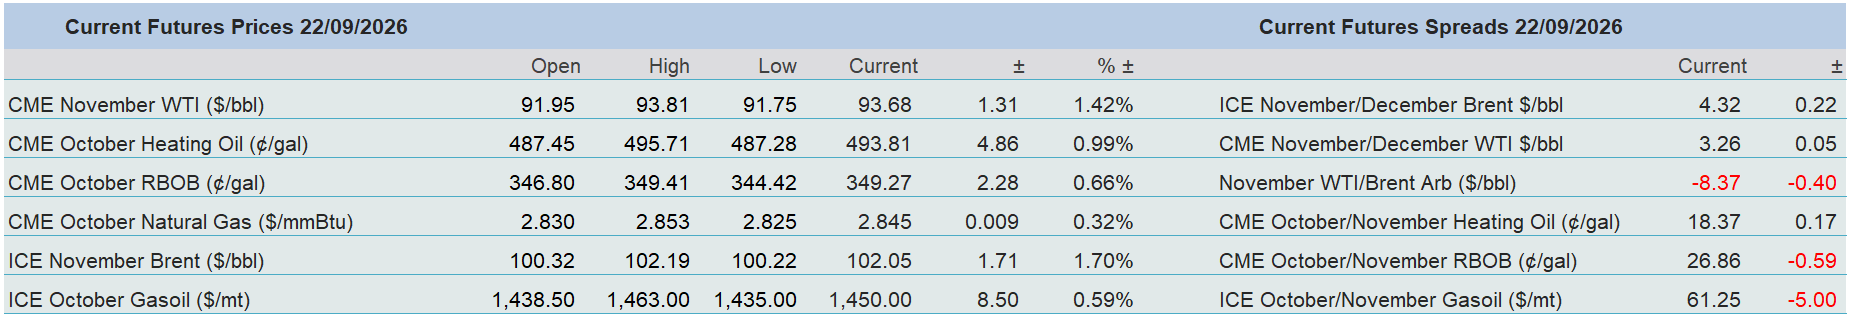
You blinked, and your position might have moved significantly against you. You were forced to limit your losses, which you might have regretted 30 minutes later. Market-moving headlines were flying around more frequently yesterday than drones in the Persian Gulf or over Ukraine. Ultimately, optimism prevailed, and it is probably not far-fetched to think and hope that negotiations to end both conflicts will intensify imminently. The two crude oil futures contracts registered their fifth successive daily losses. Still, products, particularly on the CME, held up impressively well, possibly supported, at least in part, by Hurricane Polo, which was lurking off the Pacific coast of Mexico.
We might never know whether there have been clandestine talks about an armistice between Iran and the US in recent days. Nonetheless, the US President promised not to attack the Houthi rebels, Iran pledged to reopen the Strait of Hormuz if the US meets its conditions, and Saudi Arabia is reportedly starting up the East-West pipeline while also offering spot crude oil cargoes outside Hormuz. In his characteristically combative speech in front of the UN General Assembly, President Trump envisaged a deal with Iran after the US midterm elections — or its annihilation. Although the Eastern European foes continue to attack one another, US pressure on Russia, but chiefly on Ukraine, is explicitly increasing in an effort to halt assaults on oil refineries amid the burgeoning diesel crisis. Talks of a possible US diesel export ban are getting louder, hence the overnight sell-off in Heating Oil despite the API recording weekly drawdowns in distillate (and gasoline) inventories.
Yesterday was a complete mess, to such an extent that the upcoming US-China summit, the US-Greenland-Denmark deal, and the closure of the Libyan Sharara pipeline did not even make it onto the list of the day’s most salient events. Again, the newly found consensus is one of a brighter future and de-escalation, both in the Persian Gulf and in Ukraine. Whether it will actually happen remains to be seen — what an obvious cliché. Below, we examine what might be the worst-case scenario in the event of an all-out, but hopefully improbable, flare-up in the conflict between the archenemies, the US and Iran.
Lethal Weapon 1-2-3
The end of the latest chapter of the Middle East conflict between Israel and Iran is anything but straightforward. What is undeniable is that it was triggered by the Hamas terrorist attack on Israeli civilians in October 2023, with reverberations that were plausibly not envisaged by the instigators; otherwise, they might have reconsidered. The response was justified; the extent of it was probably not, if measured in civilian lives. Nonetheless, the direct consequence of the war between the Jewish state and the Iranian proxy was US involvement, which duly started in March this year.
Similarly to Hamas’s miscalculation, the US, in the sugar rush following the blitzkrieg in Venezuela and the capture of its former president, misjudged how quickly it could achieve its objectives in Iran; faster than you can say Ayatollah Ruhollah Khomeini, it was believed. These objectives included the removal of the autocratic regime, which never shies away from oppressing and even killing its own people, the destruction of its missile capabilities, and the prevention of the Persian Gulf nations acquiring nuclear weapons. The initial timeframe for accomplishing these objectives, according to the prevailing narrative, was four to five weeks.
If the original objectives are used as a baseline, the conflict from the US perspective has proven to be a disaster, which, whether intentional or not, has never been mitigated. Almost seven months after the start of the conflagration, none of the original targets has been achieved. The biggest oversight, it seems, has been misjudging the Iranian regime’s willingness to go as far as necessary to remain in power, not only to resist US military and economic pressure but also to retaliate. And the most potent weapon has been impeding the flow of oil out of the region.
Its leverage is enormous. The Strait of Hormuz, in peacetime, is responsible for about 20% of the world’s crude oil and petroleum liquids flows. The statistical arm of the US Department of Energy, the Energy Information Administration (EIA), put the total volume of oil travelling through this chokepoint at 21.8 mbpd in 2023, which then declined to 20.9 mbpd in 1H 2025. The number of cargoes currently transiting the Strait depends on geopolitical conditions. It is, however, an undeniable fact that oil exporters in the region, although shipments have considerably declined, have demonstrated remarkable adaptability in alleviating the damaging impact of Iran’s nefarious approach to the war.
When broadening the horizon but staying in the region, Iranian sway over maritime traffic in general and oil transport in particular is nothing short of frightening. Through its proxies, it can do much more harm than simply shutting off the Strait of Hormuz, which in itself could border on economic disaster. Think of the very recent flare-up. Iranian allies in Iraq, operating under the umbrella of the Popular Mobilisation Force, launched successful drone attacks on the 7 mbpd East-West pipeline, which has lately been responsible for shipping anywhere between 4 and 5 mbpd of Saudi crude to the Yanbu export hub. Almost simultaneously, Yemeni Houthis made unexpected advances and captured around 130 km of the Red Sea coastline, jeopardising the critical shipping lane via the Bab el-Mandeb Strait.
The third alternative, albeit much longer, is the shipping route that leads through the northern part of the Red Sea, via the Suez Canal and the Sumed pipeline running from the Red Sea to the Mediterranean Sea. Traffic through this route was effectively impeded by the Houthis in the immediate aftermath of the 2023 Hamas attack on Israel and the resultant Israeli counteroffensive in Gaza and has never recovered. Extending the above-mentioned EIA estimate to these additional two pivotal waterways, one finds that Iran, directly or indirectly, can impact the transport of a significant volume of oil and petroleum liquids. In 2023, in addition to the 21.8 mbpd flowing through the Strait of Hormuz, the Suez Canal and the Suez-Mediterranean pipeline handled 8.87 mbpd of flow, with the Bab el-Mandeb Strait responsible for transiting 9.3 mbpd. Add them together, and you’ll find that 39.9 mbpd of oil was shipped through these three passageways in 2023, compared with, depending on the data source, anywhere between 25 mbpd and 30 mbpd in 2026.
Paralysing traffic through these waterways concurrently and devastatingly is unlikely, especially now that the seven-month-old conflict is, hopefully, winding down, although there are no guarantees. Yet the above roundup indicates that, in the current geopolitical and geoeconomic environment, geographical chokepoints can and probably will play a much more vital role than before in achieving one’s objectives.
Overnight Pricing
23 Sep 2026
