Calming Nerves but No De-escalation
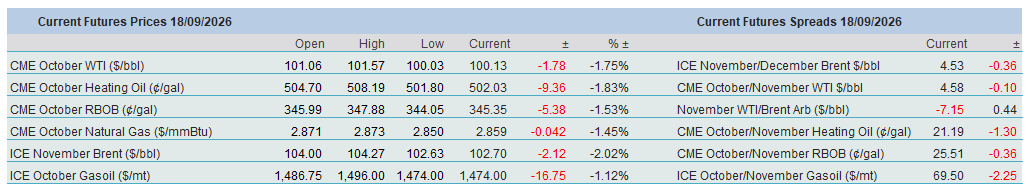
A day of two halves saw oil prices plummet, followed by a semi-decent recovery. Curiously, Heating Oil, which had blazed the trail higher recently, was hit the hardest, while the CME RBOB contract defied gravity and produced an impressive rally. Headlines carried by news outlets cannot be accused of being misleading: fears of supply disruptions eased. While that was indeed the case yesterday, actual supply disruptions did not ease. Donald Trump’s request to halt attacks on Russian refineries has fallen on deaf ears. Ukraine has struck another Russian refinery. Saudi crude oil exports from Yanbu have not resumed, and three pumping stations along the East-West pipeline have been damaged. Some relief came in the form of reports that the availability of Saudi crude oil is on the rise at the Omani port of Sohar. Yet tensions between Saudi Arabia and the Houthi rebels continue to simmer; the East-West pipeline remains closed, and the Kingdom’s oil exports will likely decline this month.
In equities, Wednesday’s sell-off, triggered by the US rate hike, was reversed, and the major indexes did their best to claw back yesterday’s losses. The Bank of England decided to leave borrowing costs unchanged but warned of further tightening in the event of persistent inflationary pressure. The Bank of Japan, on the other hand, followed the US central bank and increased its benchmark interest rate by 0.25% this morning. The oil market is having to deal with supply disruptions, while central banks are dealing with the consequences of this deficit: elevated consumer prices. Will today bring further pre-weekend long liquidation, or will the smart money be on intensifying aggression between adversaries? This morning’s price action suggests the former.
Public Debt Raises its Ugly Head
The signs are troubling. Dark clouds are gathering over the global economy. One needs to look no further than the bond market. Earlier this week, the benchmark US 10-year Treasury yield shot above 5%, for the first time since June 2007, apart from a brief spike above this milestone in 2023, in the run-up to the global financial meltdown. The comparison is alarming, as nearly 20 years ago the MSCI All-Country Index plummeted 60% in less than two years. High energy prices, driven by two conflicts centred on oil fields, refineries and pivotal transport routes, are adversely affecting the global economy, pushing up consumer and producer prices. Inflationary pressure supports higher bond yields, triggering a rise in mortgage rates and making capital more expensive. The recent and ever-so-loud calls for a pause in AI development are also weighing on investor sentiment. These headwinds are compounded by the unstoppable rise in global public debt.
Worldwide government debt has been rising for the better part of the century, and the pile has grown disproportionately larger since the financial crisis. Governments had to manage a debt pile of roughly $20 trillion in 2000, rising to $35 trillion by 2007. That was when debt issuance intensified, swelling to $70 trillion by 2019, $102 trillion by 2024 and an estimated $110–115 trillion this year. As governments spend more than they collect every year, the annual budget deficit is added to the existing debt burden, culminating in the above-mentioned stratospheric figure. No doubt, the financial crisis and the COVID-19 pandemic left governments with little choice but to support the financial system, increase public spending despite plummeting tax revenues, support households and increase healthcare spending.
Post-Covid factors include an ageing population, particularly in the developed part of the world, and, given the end of globalisation and the resultant geopolitical upheavals, rising defence spending. Ensuring energy security is also a costly exercise and, increasingly, a necessity. Trade and economic wars fit perfectly into this list. It is disturbing to realise how political myopia and ideology can deteriorate public finances. It is against this backdrop that governments have to decide how to manage the growing debt burden.
And there are no good choices. In a way, rising sovereign debt is a self-reinforcing phenomenon. The higher the annual deficit, the more the government needs to borrow. And the more it borrows, the higher the interest rates lenders will charge, widening the deficit and increasing public debt further. The IMF projects that global sovereign debt will reach 100% of the value of global goods and services in about three years.
A growing debt pile means swelling financing costs, which are currently estimated to be around $2 trillion in OECD nations, or 3% of their GDP. As pointed out in the Financial Times, the UK, France and the US spend more on servicing their national debt than on defence. The current situation is made even more dire by the recent jump in bond yields, which makes servicing these liabilities progressively more expensive. No wonder, then, that the US, which owes $40 trillion to its lenders, is adamant that interest rates must come down, whatever the effect on the domestic economy. It now actually borrows money to refinance its debt.
Soon, governments will face the burdensome and unenviable choice of tax increases or cuts in public spending – or both. It can and should also be called what it really is: the introduction of austerity measures. A further mitigating factor could be a boost in productivity, especially with the help of the artificial intelligence sector, which could stimulate the economy and increase tax receipts, but this will prove an enormous challenge to achieve in a responsibly regulated fashion. Whatever the case may be, since the era of cheap money appears to be irrevocably over, reducing government debt is unlikely in the medium term. This will ensure elevated borrowing costs, leading to fiscal discipline, which is unlikely to cause a recession but will act as a tangible impediment to economic prosperity, with all the unwanted consequences for oil demand growth.
Overnight Pricing
18 Sep 2026
