Change is Good, Only When it Comes
There is a strange geopolitical coincidence giving pause for thought or thought to pause in the progress of oil prices today. Following on from Qatar’s overtures in Tehran over the weekend, Saudi Arabia, Türkiye and Pakistan continue to press for peace and the talks which started with Iranian representatives yesterday look set to be ongoing, although timelines are unclear. With Houthi attacks unabating, there seems little reason to believe any success will come but hope in this war tends to find any port in this storm to reside.
Meanwhile today sees a general election in Israel. It is odd that the vote is described as the most consequential in years, but the outward face of the Knesset, the Israeli parliament, looks unlikely to change. The incumbent Prime Minister, Benjamin Netanyahu, frames Iran as an existential threat and is only leashed by American permission to not go all out in attacking its nemesis, whereas his main challenger, Gadi Eisenkot, talks more on targeted military action mixed with trade pressure. Politics is always about the nuance, but on the face of it, policy toward Tehran’s regime is a matter of semantics.
The root cause of this global flux, Gaza, sees even less disagreement. The Oslo Accords, fully signed up to by Israel, was crafted in the 1990s to seek a two-state solution for Israel/Palestine. Recently, Netanyahu promised there will be no Palestinian state, with Eisenkot, according to ‘Al Jazeera’ saying, “the principle of two states for two peoples is a mistake.” Whatever differences there may be in arguing internally over West Bank settlers or military conscription immunity for Orthodox Jews, any coalition formed to govern will not come with a bannered ‘peace in our time’.
It's all in the rotation
This will be another huge week for results. With the central bank decisions of both the United States and Japan already pricing in a push on interest rates, there is little in terms of tier-1 data that can deflect concentration on what the prospects of ‘Alphabet (Google)’, ‘Microsoft’ and ‘Amazon’ might be. It will take a braver missive than ours to call a bursting of the A.I. bubble, but there can be little doubt the one-way moonshot that has been the cosmic driver to the tech phenomenon has been solely driven by interest in what can be achieved by computer generated cerebralism. And whatever spends there will be to keep this self-fuelled idealistic rocket blazing, its glory is experiencing uncomfortable scrutiny.
Last week ‘Meta Platforms’ reported its third-quarter revenue increasing by 26 percent year-on-year with nearly a billion more dollars earned above the consensus of expectation. But the Achilles heel that once was covered up by eye-watering returns, has been exposed in the form of spending. Whether or not scrutiny turns to panic is for posterity, but the simple economics of outlay versus returns is so steeply skewed as to make any form of modern accountancy, even with the tolerance given to tech companies, a justification nightmare. Taking Meta in isolation, Q3 earnings came in at $64.6 billion, but raised the lower end of its full-year capital expenditure (capex) guidance to a range of $135 billion to $145 billion. This reckons not with future spending commitments, including leases, computing deals, and energy agreements, surging to $825 billion, up from the $700 billion it assessed in July. The need for further share offerings, whatever form of class, is underway to negate the possibility of cashflow issues.
There is now spending across hyperscalers and those that build data centres running into the hundreds of billions. The pace and appetite of accruing debt by A.I. names give little sign of abating and there is an impression that they are spending money that they have not even borrowed yet. ‘Merril Lynch’, now part of Bank of America used to have the moniker of the ‘Thundering Herd’ in the 1970s because of the number of brokers whose aggressiveness literally trampled competitors. These days the thundering herd does not reside in one stockbroker, it is the remit of the incredible array of investors from day traders to bond gods and none are immune from market psychosis. Hyperbolically going from a poker-style ‘all in’ to ‘all out’, these reversals of positioning are charitably deemed ‘rotation’. But rotation suggests a shift from one sort of length into another and that is where it becomes interesting for us ‘Oilies’.
Much of the work seen in last week’s rally across the oil suite was initiated on Thursday, the first full trading day after the ‘Meta’ results were published. The 7 percent rout in the ‘Facebook’ owner caused a mini crisis across the tech name spectrum, and the bourses that represent them all took a bloody nose. One of the main beneficiaries were bonds, as they suddenly became en vogue as places of haven. However, with recent financial results of oil companies cutting a media swathe, flight money also landed in the energy sector and when that happens, hedging against oil company share price involves being long ‘price’.
It is too early to say whether institutional investors are coming back into oil flat price at right angles, but the environment is becoming more attractive. The rolling up of backwardation serves as two persuaders for length. Not only does it preclude the notion of tanking oil for any sort of ‘storage’ strategy, but the heavy premiums across all contracts are a delicious bonus when flat price longs need be rolled. Bullish consistency is starting to play out. The desperate soliloquys to bring oil prices down of one Dondald J. Trump have lost all their power and downward corrective volatility is diminished. Every time reports such as the ‘Washington Institute for Near East Policy’ saying October has been the worst month for attacks on shipping in Hormuz or the IEA chief, Fatih Birol, seeing no credible path back to pre-war levels in 2027, another barrier for money managers to enter our market is eased.
If we accept that inflation, while not runaway, is very much likely to increase while the horror of Hormuz plays out, then the successful price rise hedging of being long oil will act as further encouragement for investment tourists, money managers and long-only funds alike. We await the results of more mega-caps with much interest, and if, like ‘Meta’, their debt sees another bout of rotation and if, any ensuing money being flung out of tech, lands into the oil price.
Overnight Pricing
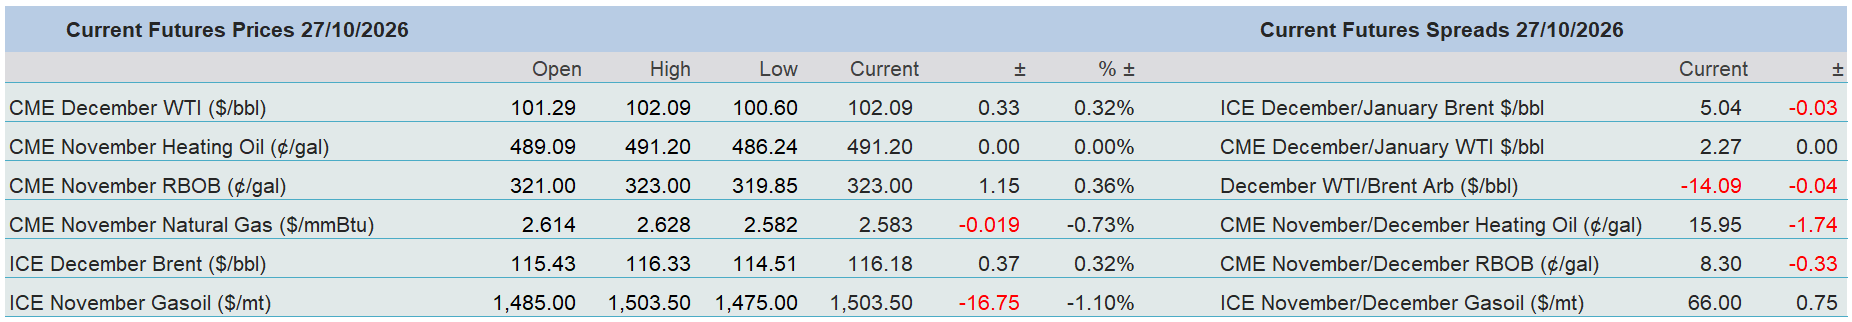
27 Oct 2026
