Change is a Matter of Perspective
Now that Donald Trump has been served a political bloody nose in the US Mid-Term elections, losing both houses of Congress, he may now be viewed as a ‘lame duck’ President, unable to fulfil any sort of legislative agenda and probably having to turn into a President of veto as the Democrats embark on pushback against the last two-years of MAGA. While we are all interested in the intriguing domestic politics of the most powerful nation on the planet, it is to how America might change its face to the world or indeed whether markets can expect any political sea change to be thus emulated in financial outlook.
Frankly, the answer is no to both. He is a man of behavioural boorish consistency it must be said, and his, “if I were on the ballot there would have been a landslide” explanation to the election drubbing, means his popinjay antics might become even more pronounced. Political commentators are now expecting a bout of staff purging and scapegoating (watch out Pete Hegseth) in his quest to deflect any sort of blame away from his Presidency. And rather taking and not talking any sort of collaborative approach with Congress, we can now expect Mr Trump to test the limits of his executive authority with unilateral decisions let run amok and many, many more visits to various courts as they are challenged.
However big the political sweep might be, it is questionable whether there will be much of a market one. Yes, greater scrutiny on A.I. buildouts will feature, particularly as there is already a groundswell of opposition being witnessed in the USA and beyond against unsightly and resource-draining data centres in agricultural or sensitive geographical settings. As for the American governmental economy itself, there is likely to be a torrid bout of political point scoring whenever spending or budget requirement decisions are due. Such political shenaniganry must only be bad for the rating of the US Dollar in terms of a place for foreign investments. But expectations of a stock market rout ought to be contained within the parameters of a so-named ‘risk clearing event’. There is intriguing analysis from ‘CNBC’. In the aftermath of a Mid-Term, the S&P500 often wavers or drops around 0.5 percent the day after a midterm, one month later reverses to gain between 1.7 and 3.4 percent, and after 12 months is higher 100 percent of the time across all 20 Mid-Term cycles since 1946, averaging a 14.4 percent gain. ‘Rotation’ might be under way as concerned tech longs seek some haven in traditional industries, hence the rally in the Dow Jones Industrial Average, therefore it is not a baby and bath water exit. Progress will be much more concerned with Federal Reserve policy and corporate earnings rather than political intrigue or deadlock.
As for our market, there are no such data to rely on, although a positive outlook for the S&P500 can never be bad for oil demand. Yet our price is emotionally involved in two game changing wars. The one on the European border, that has descended into a meat grinding hell, will see no respite, from, this war’s point of view, now emerging as inconsequential US election. Ukraine has not been given a fleeting glance in the Democrat Party’s euphoria. The pressing question is whether the already unfolding political battle against the US President’s deal with Moscow to import Russian diesel will gain greater kinetics and the H.R.6968 - Ending Importation of Russian Oil Act of 2021-2022 be once again enforced. There might be an impossible situation where there is an arguably pro-Putin US President trying to face down a pro-Ukrainian Congress. Pick the bones out of that one, so to speak.
The other conflict, dare we call it a war, has a more pressing effect on oil prices. In terms of influence brought to bear by a changed Congress, the Trump-named “little excursion” into Iran, might too be more muted than it would first appear. Some of the newly elected Democrats have ridden into victory on a chorus of anti-war slogans. However, this US President has been adept at circumventing Congress and any attempt to convert this vote-popular mandate into policy will be met by a Donald Trump more than willing to ignore war resolutions and flourish his veto. The obvious move is to denude the US military of further funding for the war in the Middle East. However, which politician would be politically suicidal enough to open themselves up as being the cause of why American servicemen and women are doing battle despite a skinflint government?
Still, oil prices have little choice other than to respond dramatically to the downside. Quantifying risk premium is impossible, but the Senate Democratic leader Chuck Schumer saying Democrats would end the Iran war must come with reaction. His is a new voice on the block and rightly deserves attention, but one wonders if this can be followed through. After all, and as pointed out in the Wall Street Journal, in June, both chambers adopted a largely symbolic resolution directing the president to cease hostilities. The House passed a similar measure in September, with the support of seven Republicans, yet the war abides and it is also worth noting that whatever influence the new Congress might bring to bear, it can only happen from January next year. So, what is the geopolitical status of everything that concerns our and the wider markets after this blown-out-of-all-proportion vote, well, it is a status quo.
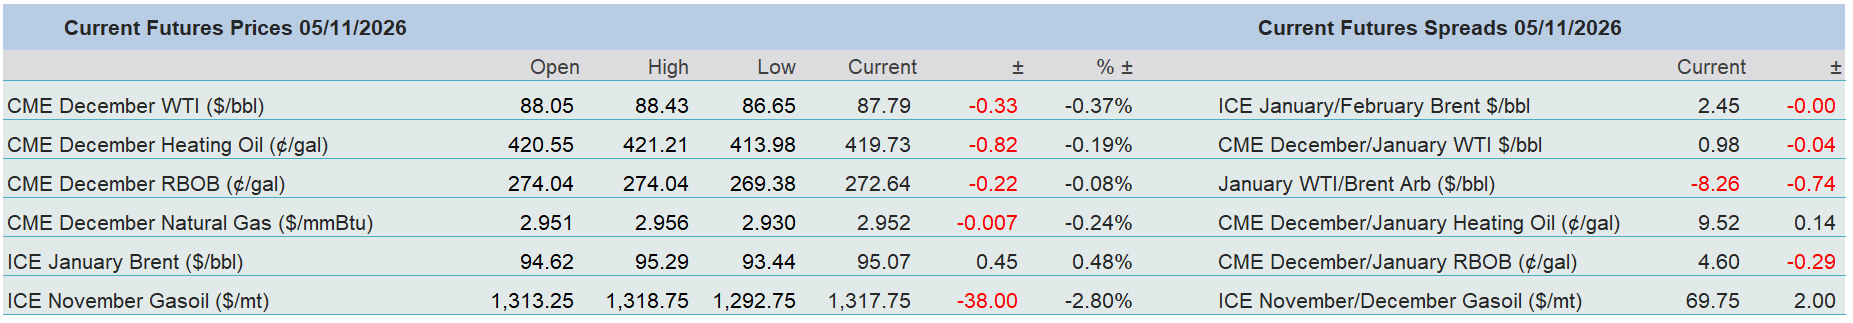
Overnight Pricing
05 Nov 2026
