Chaos Compounded
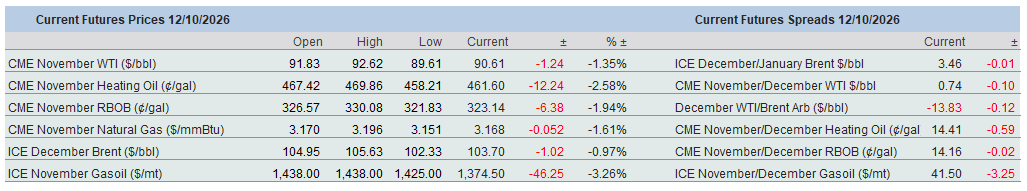
Financial and commodity markets are currently all about oil. In peacetime, oil investors tend to follow the sentiment of the wider investment world; during wars, they shape it. Energy-induced inflation, coupled with political turmoil in France, is putting enormous pressure on bond yields, making public debt increasingly difficult to service and heralding tax increases and spending cuts further down the line. Government bond yields hit multi-decade highs last week, while stock indices edged higher with the help of their greatest ally, AI. Oil was volatile as tensions flared in the Middle East, with the major concerns centred squarely in the middle of the barrel: Heating Oil gained over 5%, while Gasoil rose by nearly 10% last week.
The US administration, probably belatedly, is resorting to drastic measures to bring down diesel prices ahead of the midterm elections. Over the weekend, the US President allegedly struck a deal with Russia to supply 300,000 tonnes of the product to the ‘American and Global Marketplace’ immediately, followed by 500,000 tonnes in November and another 1 million tonnes thereafter, whatever that means. The agreement comes barely three weeks after the introduction of US legislation to sanction anyone importing Russian oil and gas. On the one hand, it represents a spectacular betrayal of Ukraine and its allies, who openly and vehemently criticised the move, which could provide Russia with invaluable financial support to continue waging its war against its Western neighbour. On the other hand, it is a questionable way to remedy the US administration’s shortcomings in its ongoing war in the Middle East, the alpha and omega of the domestic troubles the Republican Party has been forced to contend with.
The immediate impact of the deal is questionable, as Russia’s refining capacity has been severely reduced. However, Moscow has partially lifted its ban on diesel exports, allowing 500,000 tonnes (around 3.7 million bbl) to be released onto the international market—equivalent to roughly one day of US consumption and around 13% of global demand. It came as no surprise, then, that shortly after the announcement, the US President reported an immediate energy ceasefire between the warring nations, which took Ukraine by surprise and triggered no confirmation from Russia. The market’s gut reaction has been a sell-off this morning, with many more twists and turns anticipated in this surreal, truly Trumpesque charade.
Meanwhile, just two days after pledging not to attack Iran before the midterm elections, the US military struck a commercial ship attempting to break through the US naval blockade of Iranian ports, while Houthi attacks on Saudi Arabia were also escalating. In the latest atrocity, 14 people were killed and 319 injured in two missile strikes on Riyadh airport. The regional conflict is bound to escalate, and the US is now contemplating providing support to Saudi Arabia, just a few weeks after denying it.
Truce Cannot Come Swiftly Enough
It was meant to be a blitzkrieg, with all objectives accomplished within four to five weeks. These goals were to remove the Iranian regime, deprive the country of its nuclear capabilities, obliterate its long-range missile programme, and sever its ties with regional proxies such as Hamas, Hezbollah, and the Houthis. The conflict is now in its eighth month, and none of these objectives has been achieved.
Instead, Iran retaliated in every way it could, brazenly deploying the most devastating tool at its disposal: the closure of the pivotal Strait of Hormuz, through which 20 mbpd of crude oil and refined products normally pass in peacetime, along with vast quantities of other raw materials and critical minerals. The response appeared to catch the US off guard, as it had no contingency plan to mitigate or eliminate the impact of the closure. Researchers and analysts have frequently focused on the damage the conflict has inflicted on all parties involved, including those that refused to join it.
Global and regional economic growth has been impeded. The primary objective of central banks is now to rein in inflation driven by rising consumer and producer prices, while the US, whether tacitly or explicitly, is becoming increasingly isolated on the international stage.
Yet the extent of the damage remains the subject of intense debate. The head of the International Energy Agency called the conflict "the greatest global energy security threat in history". Many will still recall estimates, including our own, that forecast oil prices reaching or exceeding $150/bbl. Notwithstanding the scaremongers, the oil market proved remarkably resilient, while policymakers were admirably nimble and flexible in their response. Producers outside the Persian Gulf ramped up output; the coordinated release of 400 million barrels from strategic petroleum reserves helped calm nerves; China's cutback in crude oil imports eased market tightness; drawdowns in commercial inventories provided additional supply; and the increased use of alternative energy sources further alleviated anxiety. Persian Gulf oil producers proved particularly innovative in restoring exports to near pre-conflict levels.
Nevertheless, the destruction caused by the ongoing confrontation between the US and Iran in the world's most important oil-producing region has not gone unnoticed. Attacks on refineries and LNG facilities have caused considerable damage that will take time to repair. As the war spread from the Persian Gulf to the Red Sea, the vital Saudi pipeline and, consequently, the equally important Yanbu export terminal became temporarily inoperable. Intriguingly, forecasts of $150–$200/bbl proved spot-on when applied to physical crude oil and refined product prices, particularly diesel.
As noted above, the damage is evident. Its scale is most vividly illustrated by the burden imposed on US consumers. Forget the estimates from the Congressional Budget Office, which put the cost of military operations at $38 billion at the beginning of August, with the figure rising by $2–3 billion per month. That amount is dwarfed by the calculation below. In fact, the resulting figure is so large that we checked our assessment several times to ensure its accuracy.
It is well established that, as a result of the war, the US has become the de facto swing exporter of refined products, driving up domestic gasoline and diesel prices and fuelling discontent among drivers, farmers, consumers, and voters. Between March and September, retail gasoline prices rose by 90 cents per gallon to $3.92/gal, while diesel prices increased by $1.72/gal to $5.37/gal compared with the corresponding period in 2025. Using consumption figures of 8.88 mbpd for gasoline (373 million gallons per day) and 3.76 mbpd for distillates (158 million gallons per day), the total additional cost over the 214 days between March and September amounts to approximately $130 billion: $72 billion for gasoline and $58 billion for diesel and other distillates. These are astonishing and, frankly, unsustainable costs imposed on US consumers, starkly illustrating the Herculean task of bringing inflation back down to 2%.
It is not unreasonable to extrapolate the US experience to the rest of the world, although precisely quantifying the cumulative economic pain caused by war-induced inflation is impossible. What can reasonably be deduced, however, is that only de-escalation and a truce offer a potential path back to the pre-conflict status quo. And the weekend’s impromptu US-Russian diesel agreement and the self-proclaimed ‘energy ceasefire’ are not it.
Overnight Pricing
12 Oct 2026
