Cutting Through the Noise
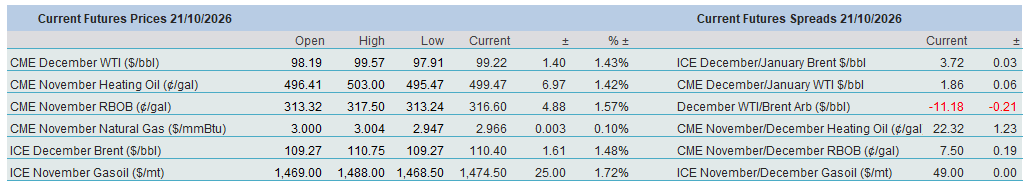
The combination of an IEA pledge to release more oil from strategic petroleum reserves if needed, a high-level Iran-Pakistan meeting, and the reappearance of Russian diesel on the international market provided a convenient excuse for profit-taking. After Brent's rally to $112/bbl, even tentative signs of additional supply or diplomatic progress were enough to tempt traders with a bullish bias to bank some profits. Whether this was justified is debatable, as neither of the two geopolitical conflicts underpinning the market's bullish sentiment has shown any signs of de-escalation. But markets trade the news of the day, and every contract, bar Heating Oil, settled lower on the day.
The $3/bbl jump from the day's lows, nevertheless, implied that the weakness would be transitory. After all, the energy watchdog of the OECD group said it stood ready to make more oil available if needed, although the timing and volume of the current accelerated releases are up to individual countries – hardly a reassuring statement. Iran and Pakistan discussed renewed mediation efforts; however, experience suggests that a breakthrough should not be expected from the meeting, while tensions in the region continue to simmer. After the US lifted sanctions on Russian oil, Kpler, as cited by Reuters, spotted two tankers carrying a total of 600,000 tonnes of diesel, presumably destined for Brazil and Turkey. The data provider estimates that Russian diesel loadings averaged below 200,000 bpd during the 10 days between October 11 and 20. The noise surrounding rising supply quickly died down, and supportive factors remain in place for now, as illustrated by the across-the-board draw in US oil inventories, reported by the API post-settlement.
Spectacular Rebuff
“Never in the field of human conflict was so much risked by one man for so little. Donald Trump is threatening to cripple Ukraine in its fight for survival—and to expose Europe to Russian aggression—seemingly for the pitiful prize of minimising his losses in next month’s midterm elections. The hard question is what Ukraine and its allies should do.” This is The Economist’s take on the latest foreign policy moves by the US Administration in its effort to gain the upper hand ahead of November 3.
And oh, boy, have there been several attempts to rein in inflation, a self-inflicted wound precipitated by the war in the Middle East and exacerbated by the conflict in eastern Europe. The first tacit admission of the unmitigated disaster the Iranian conflict had brought upon the US economy and, consequently, the Republican Party’s chances of doing well in two weeks came at the end of August, when the White House sought relief from biofuel-blending requirements for small refineries, prompting fierce protests from the agricultural sector. Restricting or outright banning diesel exports, however loudly the idea was communicated, was dead on arrival, as the oil industry made it abundantly clear that the long-term damage would far outweigh any short-term gains, if there were any. Additional measures included invoking the Defence Production Act to boost output, expanding access to tax-exempt, off-road dyed diesel, and waiving hours-of-service rules for truck drivers through the Department of Transportation.
The most significant attempts, nonetheless, targeted allies and foes almost simultaneously. Pressure on the IEA resulted in a commitment to release 100 million bbls of crude oil and diesel from strategic reserves. The highest hopes, however, rested with Russia. Sanctions were lifted to enable Moscow to export 300,000 tonnes of diesel immediately, 500,000 tonnes in November, 1 million tonnes immediately thereafter, and 3 million tonnes within a short period, according to the US President’s account of the agreement in a related Truth Social post. Another effort to increase diesel supplies included suspending restrictions and tariffs on Russia under the Graham Act and launching. Additionally, an $8 billion support programme for US farmers has just been launched to mitigate the impact of high retail diesel prices in the US.
The US administration is not short of ideas, but it has very little to show in terms of success or effectiveness. The first attempt to bring down diesel prices was the planned relief from biofuel-blending requirements on August 26. The CME front-month Heating Oil contract settled at 400.85 that day. Yesterday, it closed at 492.50. The Heating Oil/WTI crack spread has risen by $7/bl in the interim. According to the EIA, truck drivers and farmers were paying around $5.60 per gallon of diesel at the pump at the end of August, just shy of the previous all-time high of $5.81/gallon. That record has since been surpassed, with a gallon of diesel costing $6.32 yesterday.
This is a brutal snub of the government’s efforts to curb galloping prices and suggests panic, leading to reactive rather than proactive policymaking. Although limited in scope, Canadian diesel exports to the US could be increased to ease the pain. The same cannot be said of Mexico, which relies on US shipments. The re-emergence of Russian exports, even if some diesel ends up in the US, should have no material impact. The 500,000 tonnes allegedly earmarked for November equates to around 124,000 bpd of diesel supply. The US consumes that volume in about 40 minutes. Given Russia’s severely constrained refining capacity, the prospect of significant Russian volumes reaching the market, beyond the rhetoric, is highly questionable.
Relief could come—or, rather, should have come—from the Middle East. Imagine if the 3 mbpd of refining capacity that had been shut down were still available. There is little doubt that the region’s 3.3 mbpd of product exports recorded in 2025 would then be within touching distance. Instead, as observed by S&P Global, Middle Eastern diesel exports to Europe, for example, fell to a six-year low of 110,000 bpd in September, down from more than 700,000 bpd in March 2025 and January 2026.
It is difficult to find any economic or business rationale behind the latest series of decisions by a transactional President seeking to tame rising energy costs. Oil bulls and the Russian bear, however, are ecstatic; the Republicans’ prospects in two weeks look ominous, while Ukraine and its steadfast allies are increasingly distraught by what appears to be an abominable betrayal by their former comrade.
Overnight Pricing
21 Oct 2026
