Damp Squib, yet Ominous
The eagerly awaited summit of the US, Chinese and Russian leaders was short on concrete pledges. The release of the so-called joint ‘peace declaration’, which emphasised that nuclear war can never be fought, or promised to increase oil production ‘for the benefit of all nations’, appeared to be an upbeat nothingburger. For sure, the 90-minute get-together certainly boosted the US President’s morale following the bruising midterm election and reinforced his Russian counterpart’s belief that Moscow is, in fact, a force to be reckoned with on the global stage. What was conspicuously absent from the discussions was any mention of Ukraine or Iran. Yet it is impossible to ignore the fact that one of the participants is waging a military war against Ukraine and its European allies, another an ideological war against the Old Continent, while the third is exerting economic pressure on the EU.
Notwithstanding the ‘peace declaration’, President Putin threatened Ukraine with harsh retaliation following the bombing of the Crimean Bridge, hardly a harbinger of an impending truce. In the Middle East, Iranian state media reported that another two oil tankers had struck mines in the Strait of Hormuz. The Houthis fired missiles at Riyadh, while the Kingdom does not expect tensions with the Yemeni rebels to subside until after next year. While a supply surplus is widely anticipated in the coming months, de-escalation in Ukraine or the Persian Gulf is not. Uncertainty is likely to persist until January, when the Congressional lame-duck session comes to an end.
Diesel to the Rescue
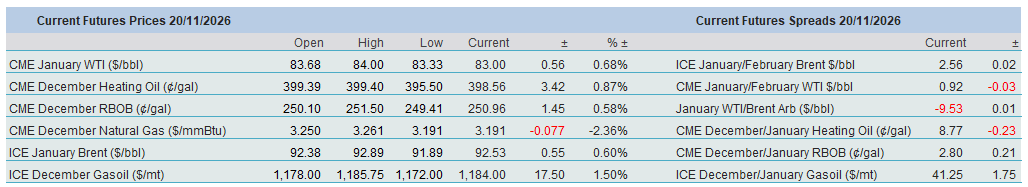
As if the switch controlling the global oil dam had been flipped right at the time of the US midterm elections, the gates had been opened, and the world had been flooded with the black stuff. Month-to-date performances are as follows: WTI -19%, Brent -18%, RBOB -20%, Heating Oil -13% and Gasoil -16%. Oil exports from the Middle East have reportedly been increasing. Global and regional oil inventories are expected to fill up rapidly, or so the thinking goes. Look no further than Wednesday’s US inventory data, which showed significant builds across the board, culminating in a 9 million bbl increase in total commercial stockpiles. Refiners are operating at a rate of 95.7%, high by historical standards. The main reason for the inventory build is that net product exports declined by 1.8 mbpd on the week, implying reduced global reliance on US refined fuels.
Will the downward move continue? Well, there are warning signs. The ongoing hostilities between Saudi Arabia and the Houthi rebels in Yemen are well documented. Of particular importance, Yemeni government forces have withdrawn from the Bab el-Mandeb Strait, leaving it exposed to a potential closure. Its counterpart, the Strait of Hormuz, is littered with mines, making shipping through this crucial gateway a treacherous undertaking. The forward curves of the five main oil futures contracts remain solidly backwardated, with the backwardation in Brent and Heating Oil having narrowed very little. Physical Brent commands a hefty premium over forward contracts. Crack spreads, while considerably lower than their September peaks, remain above historical averages.
From a subjective perspective, tensions are expected to persist in both geopolitical hotspots, as the gaps between Ukraine and Russia and Iran and the US remain ostensibly unbridgeable. This is nowhere more clearly discernible than in Eastern Europe, where continuous Ukrainian drone strikes on Russian refineries do much more than create difficulties for Russia's ability to export refined products, chief among which diesel is probably the most important.
Distillates were chiefly responsible for the rally in outright prices between June and September, to such an extent that the US administration was forced to lift the ban on Russian fuel exports in an attempt to ease pressure on domestic retail prices, despite the move contravening federal restrictions. The volumes, however, turned out to be minimal, and no cargo actually reached US shores amid legal risks.
The failure of the arrangement was almost predestined. Why? As far as domestic supply is concerned, Russia is in a quagmire, and that is probably an understatement. While reliable data is hard to come by, the IEA estimates that Russia's refinery utilisation rate was around 74%-77% before November. As both Kyiv and Moscow intensify attacks on each other's energy infrastructure, operations have been halted at 15 of Russia's 35 refineries, according to a Reuters assessment. Further scrutiny reveals that crude oil processing plunged by 45% in November, falling from 700,000 metric tonnes a day at the end of October to 400,000 metric tonnes a day in the second half of November. Reuters estimates that around 54% of Russia's total primary refining capacity of 930,000 tonnes a day has been affected. This is a huge number.
Not only has Russia's ability to export refined products been severely constrained, but the country has actually been forced to import fuel as its domestic supply crisis worsens. Data analytics company Kpler puts Russia's seaborne product imports in October at 390,000 tonnes, sourced from countries as far afield as Belarus, India, Egypt, Kazakhstan and Morocco. This is an extraordinary development for a producer that, in peacetime, refines more diesel and gasoline than it consumes domestically. It also lays bare the economic ramifications of the war Russia brought upon itself.
The upshot of all the above is that, in spite of the current weakness in outright prices, the distillate segment will plausibly establish a price floor for the entire barrel, not too far below current levels. If you buy into the IEA's argument that 'even with a rapid recovery expected in refinery throughputs into year-end, gasoil supply falls short of meeting demand in 4Q26, suggesting that the replenishment of lost inventories, outside of typical seasonal fluctuations, is unlikely before 2H27', you will subscribe to the view that the distillate market remains generally tight. Alternatively, if our prognosis that the market is close to finding a bottom proves wrong, Heating Oil and Gasoil are likely to weather the downward storm more valiantly than the rest of the barrel.
Overnight Pricing
20 Nov 2026
