Diesel Deals and Doodles
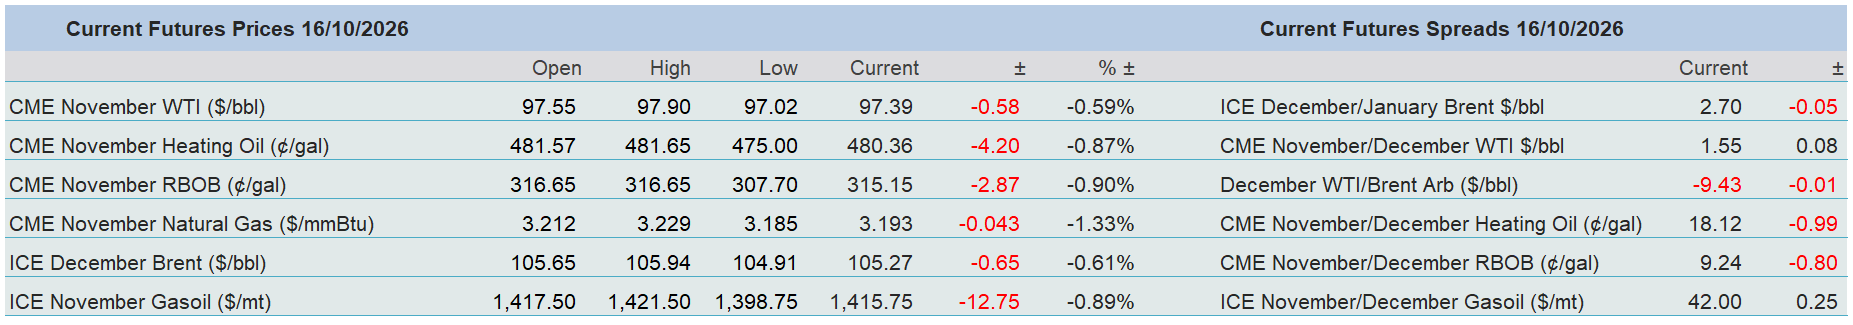
A disparity, or correction depending on one’s bent, has formed in the oil complex, and it is inspired by the recent outperformance of WTI. There are several contributing factors, some that are fairly obvious and one a little more debatable. The recent US Gulf evacuation of oil personnel due to Hurricane Isaias led to so much oil shut-ins that crude inventory drew by 8.56mb, according to the EIA inventory report, which has occurred in the face of increased refinery runs and just as CME M1 WTI futures approaches expiry evoking position trading that is looking for a ‘roll up’ in backwardation. However, what might be a silent part of the bid in the US crude grade is the influence of the floated idea on how the US President is considering relieving sanctions on parts the global dark fleet. Given the inordinate costs involved in getting US oils to the Asian market because of freight rates, an increase in the availably of shipping tonnage, and resulting fall in what it costs to move oil by sea, would cure American crudes of their current locked-in syndrome and see an increase in exports. One of these factors alone would not have moved the WTI/Brent arbitrage as much, but this confluence of drivers, real or speculated, has decreased the premium Brent enjoys over WTI by nearly $5/barrel in 3 days, as seen in the December26 futures price. The dark fleet consideration is a side-effect of the war the White House has declared on diesel prices. It is much easier for Russian tankers to immediately shift its own refined products, and more ships equals more capacity even if there is a quibble as to whether vessels are derivative or feedstock peculiar. American pressure does not stop there. Sporting a possible US diesel export ban as the whip, Washington has harried the team of Europeans led by the IEA to an agreed speeding up of SPR releases including 20mb of diesel. No doubt the IEA wishes it could turn its own transponder off and go dark. We await the next piece of oil Mid-Term election micromanagement with cynical breath.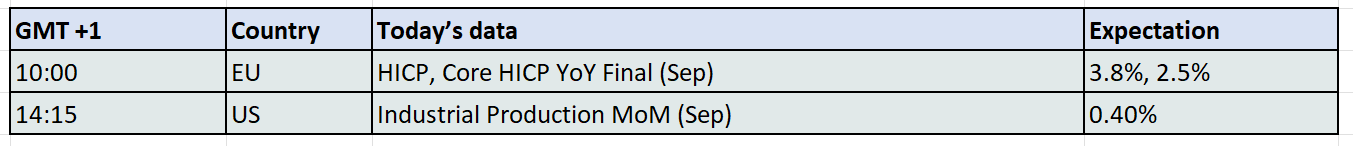
It is never much fun at an IMF party
The International Monetary Fund continues its meeting this week in Bangkok, and while it is never shy in serving up a bowl of miserable custard to any financial implications that might trouble the world, its words against the excesses within national economies and businesses do make for some troubling consideration. Whether or not the Fund would have eventually been so stark if it were not for Iranian war is ponderable, but the conflicts in Arabia and the ability of Ukraine to expand its theatre of military influence into the hinterlands of Russia have caused a sharp spike in global oil and gas prices with the ensuing inflation causing havoc to whatever form of dot-plot one might construct for future interest rates. Headline inflation in the United States has been accelerated to 3.7 percent, in the Eurozone to 3.8 percent, the UK 3.1 percent, and in the emerging but fuel import reliant economy of India, 5.54 percent.
These inflation rates and energy shocks have quickened the IMF’s reaction to burgeoning national debts which are emerging, from the dark places where nobody wants to look, into the light of scrutiny, because their size and costs to service them can no longer allow them to be something not mentioned when oil prices, A.I. buildouts and the US Dollar meet at swanky bullish dinner parties. The Fund said the effective average cost of government financing was projected to rise to 3.7 percent by 2031 from 2.3 percent in 2021. It is sobering indeed it goes on to point out how rising borrowing costs, in reaction to inflation, are intensifying fiscal pressures worldwide because at the current rate of deficit growth, global debt to GDP will move beyond 100 percent by 2030. The exceptionalism of Uncle Sam was given no quarter. IMF Managing Director, Kristalina Georgieva, as seen on ‘Reuters’, said on Wednesday, “the United States cannot grow its way out of mounting public debt without tax or spending adjustments.” Bond markets are telling a story, and governments would do well to listen.
Addressing the hot topic of the moment, well if anything can be beyond concurrent wars, the IMF spent a lengthy gaze on the state of the bond market. In its latest Global Financial Stability Report, the fund warned that sovereign bond risk could deteriorate, warning of “a sharp rise in sovereign bond yields.” How far yields might progress was an expectation too far, yet the global state of play suggests that the Fund is more than within its rights to cast a shadow of doom across what has been a successfully sunny period in the investment suites which inarguably have benefited from years of loose money and tame interest rates. Presently, benchmark US 10-Year Treasury yield is hovering around 5.08 percent (after peaking near 5.37 percent), Japan’s JGP 10-year yield reached a high of 3.11 percent before correcting but worth remembering on the last trading day of 2025 it was 2.07 percent and a year before 1.09 percent, while the UK 10-Year Gilt yield is trading at 5.37 percent, after pulling back from a 20-year high. In Europe there was almost a panic when the French part of this example topped out just before hitting 5 percent as its fiscal integrity goes through yet another season of testing.
One of the trickiest parts of any reform in spending is guaranteeing future energy supply and security. The IMF conceded, but warned, “without shoring up supply capacity and replenishing policy buffers, the global economy could soon test the limits of resilience,” it said. “Inventories in energy markets are dwindling, and additional geopolitical shocks could still transmit rapidly through prices and supply disruptions.” The Fund is very long on warnings but incredibly short on solutions as far as energy is concerned. How, for example, does Europe, much more vulnerable to energy prices because of its import requirements, achieve energy security without additional strategic spending? The ramifications of all the above are vast and variable, but none can be truly addressed until these resource, human, and fiscal sapping wars come to an end.
Overnight Pricing
16 Oct 2026
