Exports Improve, not Sentiment
In the spirit of oil always finds a way, it appears through various news agencies that more oil is navigating to market from the geographical Middle East region than at any time since the start of the war. We look at the remarkable shipping workarounds below, but ‘Kpler’, according to ‘Reuters’ estimate exports are now at 80 percent of pre-war levels. However, and judging by the obstinate way in which oil prices refuse to back off, the oil market will have to witness at least a repetition of export recovery in the next trading cycle or two for such news to calm the fears of a market caught short of everything oil-conceivable going into the northern hemisphere winter. The only thing our fraternity is long of is words. Headlines come at us at pace and none can be trusted as being either a cricketing googly or a baseball knuckleball and yesterday included mention of Iran being prepared to throw in its nuclear program as part of a settlement. Meanwhile it looks as if there are only indirect talks via Qatari mediators in New York and the flashes across media are wishful thinking rather than concrete deals. If it were not so, why is the US President still pondering a diesel/export ban and twiddling with the tax regime on agricultural ‘red’ diesel if he thought petroleum products would be soon flowing forth from the choke points of disruption he has caused via Hormuz and Bal el-Mandeb?
Ship Ahoy! If you can find one that is
It is with great interest that we read from ‘Kpler’ via Reuters on how the amount of Middle Eastern oil making its way to market has increase to a 12.8mbpd average in September. The surrounding wars on either side of its coastal regions are still having effect, but remarkably, Saudi exports have increased to approximately 6mbpd in September, bringing its crude shipments back to levels approaching the monthly average recorded in 2025, again using data from ‘Kpler’ as seen on ‘Al Arabiya’. The improvement in ability to move oil stuffs around comes as the US clears the seaway on the Omani side of the Strait of Hormuz. This has led to quite the shipping feat from the Kingdom, but it is not alone in exercising this practice and the call on the skills of the maritime heroes is only matched by the capacity needed to service this newfound phenomenon. Iraq’s oil production surged to 3.5mbpd in August as increased exports become more possible at its southern export terminals and the UAE is also achieving a similar export amount as it tries to release some of its pent-up oil production ambition after ceding from OPEC membership.
This is all made possible by the increasing use of ship-to-ship (STS) transfers which have become a critical workaround for the logistics of oil flows. There are two essential legs to what is becoming a standardised practice. The ‘shuttle leg’, being inside the Gulf, involves VLCCs or sometimes smaller capacity vessels undertaking initial loading at port and then delivering STS transfers off Sohar in Oman or Fujairah in the United Arab Emirates, the ‘meeting point’, both outside Hormuz, and then onto global destinations. There are obvious exceptions, because Chinese vessels unlike other possible targets are immune from IRGC attention due to China being almost the last destination for Iran’s crude, and an attack on a COSCO ship would be tantamount of shooting oneself in the foot. For example, and according to ‘Xinde Marine News’, under a conventional Saudi Arabia-China VLCC voyage, a tanker loads roughly 2 million barrels at a Gulf terminal such as Ras Tanura or Ju'aymah, passes through Hormuz and continues across the Indian Ocean to China. The ‘Chamber of Shipping’ estimates around 2.5mbpd are expected to be loaded through all of these transfers in September, up from 1.4m in August.
Being firm and exact on the amount of oil being moved or the shipping involved is impossible due to the very nature of the war and how ships run ‘dark’, as in turning their Automatic Identification System transponders off. However, what cannot be contested is that the oil deliveries have a verifiable two-leg journey and because of it a need for many more vessels to undertake them. It is a high-stakes game for the shuttle leg and the cost to insurance, if any can find a willing underwriter, or indeed crews. As of September 16th, the International Maritime Organization had verified 80 attacks on merchant vessels in and around the Strait of Hormuz since the current Middle East conflict began on February 28th, resulting in at least 22 seafarer deaths. Insurance cover is being crafted and is bespoke rather than a blanket cover, and it is only the current price of crude oil that stops it being prohibitive. Crude grades fetching $100/barrel is always inspiration enough to contemplate risk from ship owners.
It will be the price of crude oil and the longevity of this particular part of a Gulf War that determines the intriguing strategic playbook unfolding in shipping at present. Needless to say, the cost of building ships and their chartering is soaring. The demand for shipping has increased so rapidly that older ships are commanding greater prices than newer. The ‘Financial Times’ reports in the past week, several ships built before 2016 were sold for $150m or higher, compared with an average of $135m for new builds. Last week saw some diplomatic heat exchanged as Saudi denied buying 25 oil tankers, so claimed by Iraq as it endeavoured to lay the blame for soaring shipping rates. According to LSEG data, chartering a VLCC for a voyage originating inside the Mideast Gulf and transiting the Strait of Hormuz has reached record highs, touching daily time charter rates between $1 million and a record $1.27 million per day.
The world is now short on shipping, not only from wet cargoes but from dry bulk carriers due to the overlapping wars causing bottlenecks in key areas. Dry shipping costs are being harried higher. Taking a small part of global trade and as read in the ‘Daily Telegraph’, spot rates on the Far East-Northern Europe route, which includes shipments of clothes, electronics, toys, furniture, car parts and machinery to the UK from China, Japan and Korea, have risen 85 percent to average $4,100 per 40sq ft container since the start of the Iran war. Whatever goods being transported, be they wet or dry will now have to increase in price for producers to make any sort of turn on whatever they are putting to market.
The inflationary influence is then self-evident and circular. The less shipping there is the more competition will increase for cargo space. If the US EIA estimate on global oil inventories fell by an average of 3.9mbpd in the second quarter of this year, then a goodly part of that will be floating storage. Any VLCC being used as storage is dead money, and there is no chance of any sort of ‘carry trade’ in the near or medium-term future. Therefore, it is without surprise when using Vortexa data, global floating storage has fallen from 145mb in April to around 88mb and within that data, Asia from 40mb to just 17mb. There is no immediate cure for what is going on in freight other than a cessation of this pointless war. Oil trading used to have shipping as an ancillary cost, somewhere lower down on the spreadsheet of expenditure. Freight rates have now been elevated to top spot and at present will remain there for some time.
Overnight Pricing
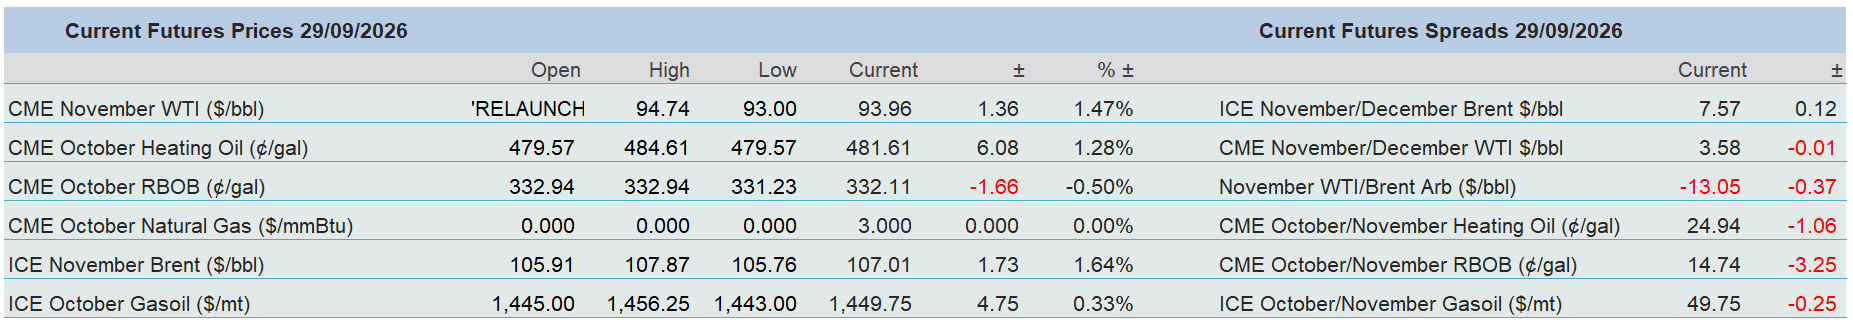
29 Sep 2026
