Handbrake turns
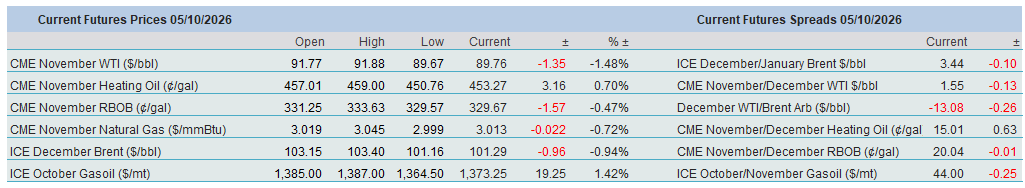
There was a sigh of relief, perhaps even some cork-popping, in Washington, D.C., on Friday afternoon. The arsonist, posing as a firefighter, extinguished the fire by coercing its partners to open the water—well, the diesel spigot. The Administration granted the US oil industry’s wish. There will be no export ban on diesel, but rather a collective release of 100 million bbls of crude oil and diesel from strategic reserves, coordinated by the IEA and reportedly spanning more than four months, ‘with a front-loaded, substantial diesel release within the first 20 days’. The move’s immediate impact was a $96/tonne drop in the price of ICE Gasoil, taking the cumulative weekly loss to $106.75/tonne, or 7.3%, while December Brent gained almost 5% week-on-week, and RBOB also finished the period in positive territory.
The SPR release is politically motivated ahead of the November US midterm elections. While one source of uncertainty has been temporarily removed from the US and European middle-distillate markets, China’s export suspension has tightened supply in the Far East. It is also an irrefutable fact that a Middle East truce is anything but imminent. Over the weekend, Houthi rebels struck Aramco energy installations in the Riyadh and Khurais areas after the Kingdom launched missile strikes against the group. The Yemeni government also began an offensive against the Houthis to recapture all areas controlled by the Iranian proxies. The SPR release will add to the burgeoning supply in the immediate future, as Middle East crude oil exports exceeded pre-war levels for four days in the last week of September, according to Kpler estimates. However, it will not be able to neutralise the risk posed by regular attacks on oil infrastructure and vessels in the region, effectively setting a floor under the market.
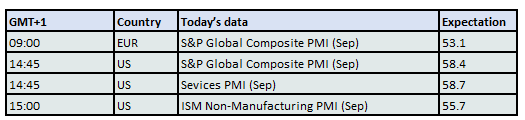
The bond market underwent an experience similar to Gasoil’s on Friday. Disappointing US labour data provided the perfect excuse to cover short positions and, hence, push yields lower. Nonfarm payrolls increased by only 29,000 in August, undershooting expectations, while unemployment ticked up to 4.2%. One of the Fed’s dual mandates is to promote maximum employment; therefore, when the job market deteriorates, bets on rate increases are scaled back. The other mandate, nonetheless, is price stability, and if inflationary pressure remains persistent, rate-cut expectations might soon be revised.
Oil and Gas Players are More Active in the US South
Any research or analysis written a day before its planned publication date risks becoming obsolete in the current tumultuous trading environment. Preparing a report for a Monday at the end of the preceding week is an even more perilous undertaking because of the extended time risk. The quarterly Dallas Fed Energy Survey, the latest version of which was released last Wednesday, offers an opportunity ‘to play it safe’. The views of executives at more than 100 exploration and production (E&P) and oilfield service companies in Texas, southern New Mexico and northern Louisiana will not have changed over the weekend. Amended views and second thoughts will be made available when the next issue is published in the middle of December. A bonus is that the publication provides valuable insight from a group of crucial participants in the oil market.
The survey, which was conducted between 16 and 24 September, used responses from 125 energy companies headquartered in the Eleventh District, 83 of which were E&P companies and the remainder were oilfield service firms. The broad conclusion was that general activity in the oil and gas sector expanded in the third quarter of 2026, despite rising costs and longer supplier delivery times. Although the index measuring business activity declined from 46.1 in 2Q to 38.8 in 3Q, the fact that it remained positive suggests solid, albeit somewhat slower, expansion. The indices measuring oil and gas production both registered quarter-on-quarter growth: the former from 15.0 to 20.7, and the latter from 3.7 to 14.8.
Cost pressures remain persistent for both E&P participants and oilfield service companies. Supplier delivery times continued to get longer. Labour conditions were a tad brighter in 3Q than in the preceding quarter. The aggregate employment and aggregate employee-hours indices both increased, and although the aggregate wages and benefits index ticked slightly lower, it remained firmly above the 0 line. The Company Outlook Index also advanced.
And now, over to the exciting stuff. Almost 50% of respondents expect the price of the US crude oil benchmark, WTI, to be between $80 and $90 by the end of the current year. In second place, with around 25%, are those who expect it to be between $90 and $100. Those who believe WTI will either be below $80 or between $100 and $110 are tied at around 10%. The mean value of all the responses was $88/bbl. For reference, WTI spot prices averaged $98.70 during the survey period mentioned above.
In the ‘Special Questions’ segment, respondents were asked to share their views on five topics: the absolute minimum US SPR level, Persian Gulf export normalisation, fuel-price spread reversion to 2025 levels, free-cash-flow allocation plans for E&P firms, and oilfield theft. The replies to the three most salient ones are as follows. As for the US SPR, 31% believed that the absolute minimum level is between 100 and 150 million bbls (the EIA showed that the current level is 284 million bbls). At the extremes, 21% see the minimum between 50 and 100 million bbls, while 19% put it in the 250–300 million bbls range. The majority thinks Persian Gulf exports will return to normal by 2Q 2027; the most ubiquitous view was that it will take more than four quarters for gasoline and diesel crack spreads to return to 2025 levels.
And finally, our favourite part of the survey: the anonymous comments. Below are the most interesting ones from E&P firms.
• War issues affect futures. Refinery capacity is the choke point now for consumer fuel needs. Domestic capacity is low and is affected by both regulations and margins.
• Oil movement around the world is the major unknown today.
• I think the Middle East conflict will last longer than most believe.
• I don’t quite understand why the price is high at the pump. The US has plenty of supply.
Overnight Pricing
05 Oct 2026
