He’s Back
Conditional reflexes were bound to kick in at some point, and that moment came yesterday. The US President has seemingly digested last week’s midterm election results and is now back to his confident and pugnacious self, the behaviour that characterised his pre-midterm days in the White House. He has rebuffed his Vice President’s criticism that the Republicans lost the elections because of the Iran war and suggested that Mr Vance concentrate on investigating domestic corruption, while making it clear that the US does not need to strike a deal with its adversary. He has threatened to double import tariffs on Mexico unless its southern neighbour halts the flow of migrants across the border into the US. He even felt the need to recommend the former Apple chief as Nvidia’s new CEO, following Jensen Huang’s resignation after his alleged romantic relationship with a Chinese spy came to light.
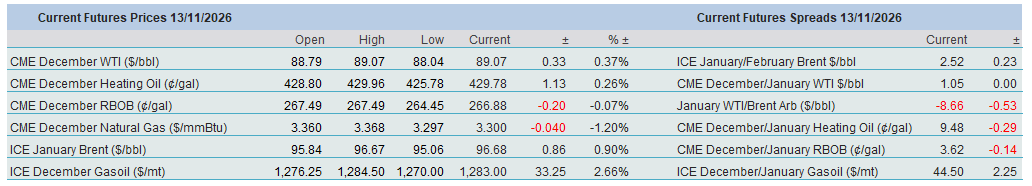
Mr Trump is no longer pursuing an armistice with Iran, and it has to be pointed out that the feelings are mutual. The oil market rallied hard yesterday as explosions reportedly hit four oil tankers in the Strait of Hormuz, while Houthi rebels claimed to have attacked a pumping station on the East-West pipeline and an oil facility in Yanbu. Meanwhile, preparations for peace talks between Russia and Ukraine are ongoing, but reciprocal attacks on oil infrastructure have not stopped. In the latest development, oil exports have been halted at the Russian port of Ust-Luga.
The geopolitical risk premium is on the rise again, yet a rally back above $100/bbl is far from guaranteed. OPEC production rose in October, notwithstanding the frequent attacks in the Persian Gulf. This issue will be discussed in detail in Monday’s note. US oil stocks recorded weekly builds across the board, while product inventories in the ARA region and Singapore also swelled. Although unpredictability is likely to prevail, in the absence of a severe supply disruption in the Middle East, the upside might prove limited.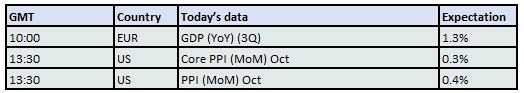
Challenging to Reconcile
Two of the three regular mid-month updates have been published this week, while the remaining one, from the IEA, will be released around the time you read this note. The EIA and OPEC have not significantly amended their recent views, although the inevitable revisions are discernible. The EIA cut its demand forecasts for 4Q 2026, for the whole of 2026 and for next year. It slightly increased its non-DoC supply estimates for the remainder of this year but significantly downgraded them for 2027. It therefore sees a declining call on DoC oil in the final quarter of the current year and a rising one next year.
OPEC made only slight adjustments on both the demand and supply sides. Consequently, the call on oil from the wider alliance was raised by 200,000 bpd for 4Q and by 70,000 bpd for the whole of 2027. The chasm between the EIA and OPEC projections of how global and OECD inventories will change in the near and medium term remains unbridgeable. The EIA expects global oil inventories to build by 1.47 mbpd in 4Q and by 4.04 mbpd in 2027. OPEC, on the other hand, envisages a global drawdown of 4.89 mbpd in the current quarter (assuming an output level of 38.61 mbpd, including the UAE) and 1.22 mbpd in 2027 (with output forecast at 42.71 mbpd). This would result in OECD stockpiles bidding farewell to 2026 at 2.739 billion bbls (EIA) and 2.631 billion bbls (OPEC). The gap widens to an eye-watering 640 million bbls by the end of next year – 3.095 billion bbls versus 2.454 billion bbls – assuming that, in OPEC's calculation, 40% of the global stock change takes place in the developed part of the world.
This brings us to OPEC's view of global stocks. The organisation devotes its Feature Article to the latest developments in global oil inventories. The broad picture is one of declining stockpiles between February, just before the Iranian conflict erupted, and September, the end of the third quarter. Over these seven months, global stocks plunged from 8.58 billion bbls to 8.043 billion bbls. The first category of global stocks, OECD inventories, fell by a combined 24 million bbls in commercial stocks (23 million bbls in product inventories, which explains the staggering rally in crack spreads, and only 1 million bbl in crude oil inventories), while OECD SPR stocks, following a coordinated release, plunged by 218 million bbls, only half the agreed volume. The US and Japan accounted for the lion's share of the SPR drawdown.
The remaining 294 million bbls of the decline took place in non-OECD nations. Developing countries, particularly China, which recorded a seven-month drawdown of 156 million bbls, were the major contributors to the global stock depletion. This comes as little surprise, since a) Asian nations were, and remain, the most exposed to Persian Gulf supply disruptions, and b) China's unprecedented reduction in crude oil imports between April and June implied a considerable drawdown of inventories in the world's second-largest economy. Finally, the volume of oil at sea remained unchanged between February and September.
As mentioned above, we arbitrarily assume that around 40% of global stock changes occur in OECD countries. While this was true before the conflict and may well become accurate again in the future, OPEC's latest data suggests, as emphasised in its Feature Article, that this share is presently a mere 35%. Using this figure would still imply a gap of 596 million bbls in end-2027 OECD stocks between the EIA and OPEC. While this approach is more than reasonable under the current, almost unpredictable circumstances, the 3Q 2026 figures are bordering on the irreconcilable. A quarter-on-quarter global stock DRAW of 4.2 mbpd has been accompanied by a 65 million bbl, or 710,000 bpd, INCREASE in OECD inventories. This, when taking into account the SPR release and the change in the volume of oil on water, implies a depletion of 5.1 mbpd in non-OECD oil inventories. Global stocks moving in the opposite direction to OECD inventories is a very rare, if not unheard-of, phenomenon. After all, to reiterate, OECD inventories still accounted for 35% of global stocks at the end of 3Q 2026.
Overnight Pricing
13 Nov 2026
