Just too Much to Consider
Where to land one’s gaze this week is matter of taste, or more likely involvement. We touch on investor anxiety below, but after the global outage of Microsoft on Friday, the grounding of US planes for more than four hours, affecting thousands of flights and passengers over the weekend, and yesterday’s outages at major US banks, including JP Morgan Chase, Wells Fargo and Bank of America, blocking customers from accessing services and money will have conspiracy theorists running up walls. Nvidia publishes its latest results after hours and it will be interesting to see how the powers-that-be in the massive tech company avoid very awkward questioning surrounding their former (at the moment) disgraced CEO.
There is also a plethora of meetings and speeches from the members of the Federal Reserve over the course of this week, kicked off by Chair Kevin Warsh at a Fed conference on A.I. in San Francisco yesterday. Noting the influence of A.I. growth and its effect on socioeconomics one can only assume he is watching the IPO of Anthropic on Wednesday with interest. However, his reluctance to be drawn on forward guidance left little for commentators to sink their teeth into, but there have been a succession of hawkish thrusts from other members with the landscape of interest rates likely outlined when the minutes of October’s meeting are published on Wednesday. At present, the market is gearing up for higher rates which is why the US Dollar Index is closing in on 20-month highs.
As for our market, it is going through the throes of trying to sort out what bottleneck premium should be valued at rather than imminent attack premium. This is represented in the dramatic fall of freight rates. As seen on ‘Reuters’, the Gulf of Oman to China route for VLCCs has fallen by 60 or so percent as more tankers are freed up to ply their craft elsewhere, despite the reporting of ships hitting mines and being subject to other assorted attacks. The IEA, never far away from a bearish call, on Friday supposed a return to surplus in global oil supply in the fourth quarter and with OPEC in the process reviewing maximum sustainable capacity of oil production, the market is now expecting more and more crude to become available. Something of a dangerous presumption given what has gone before, but we are in value discovery mode and with the end of the year drawing in, it is hard to see anyone taking huge positional swipes at whatever news might flash across very tired screens.
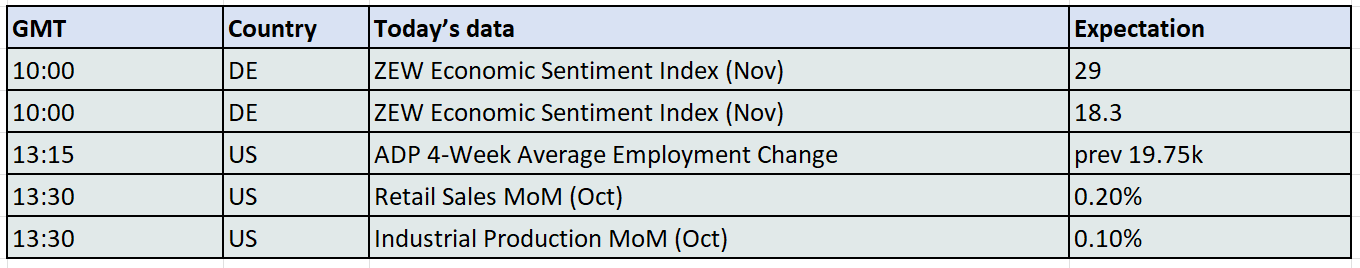
The world wishes it was flat
It is incredibly difficult to justify an argument on how any single stock might influence the price of oil, or vice versa. The relationship peccadillos of Jensen Huang, and their threat to US national security are not in themselves pivotal, and not likely to be the proverbial straw that breaks the A.I. camel’s back. The correctional tipping of sentiment in the tech stock trade has been coming for quite some time and while the Nvidia drama plays out on the world stage, it serves as a timely reminder that trading is not that easy. One does not just buy and expect stuff to automatically appreciate. Would that we could put a value on FOMO (fear of missing out), but the $1.5 trillion loss of value in the once darling of tech, give or take a few billion here or there, is a sign of evacuation by longs who in many ways were involved on the say so of others rather than by the means of studied wits.
We note with interest the ‘Fear and Greed Indicators’ compiled by ‘CNN’. In the 7 categories all but 3 are registering ‘fear’. Neutrality comes from Stock Price Breadth, that which are rising or falling and Market Volatility using the CBOE Volatility Index (VIX). The only ‘greed’ indication comes from Junk Bond Demand section but can be explained away by investor flight. Here then comes this small stab at aligning a mistrust in being overly exposed to stock prices and oil. Using the 125-day moving average in the S&P 500, the index has tracked below it since the beginning of the month and shows ‘extreme fear’ in Market Momentum. The Put and Call Options ratio is currently rising within stock markets indicating fear and importantly, Safe Haven Demand unsurprisingly joins Market Momentum in registering ‘extreme fear’ as the last 20-days show bonds offering a better return than stocks. The amalgamative score of 39, within a 0-100 scale shows continued anxiety within the wider investment suite.
At the beginning of November, the CBOE Crude Oil Volatility Index was reading 62.5, but since the shellacking meted out to the Republicans in the US Midterm elections and in terms of Iran, a much more dialled down White House, that has fallen to 50.0 and with it, open interest. Money managers have decreased their exposure to ICE Brent on futures and options to the least bullish in more than 4 months with long-only positions falling to the lowest in about 11 months. The ‘long-only’ reduction is in some ways more important because it indicates how institutional money is leaving oil shores. Not even oil’s favoured status as an inflation hedge can keep interest ticking over for long-term strategies. Brent has lost 200k lots of open interest alone this month, let alone the 1.5 million lots lost to price unreliability since the high positioning of March. As we touched upon yesterday, the ability of Gulf states to get their crudes to destinations coupled with embedded demand destruction due to price means the geographical pinch point between Iran and Oman might now be called the normal of Hormuz, where sporadic outbreaks of hostilities and diplomatic double speak ride roughshod over oil trading appetite.
Global investors, including the mercurial thundering herd, are increasingly staging bouts of rotation as they seek to find assets that can keep them in a holding pattern while the world sorts out its geopolitical and corporate fluxes. Yet, taking a look at safe havens, be they against inflation and higher interest rates or Nvidia-type fallouts, they are often found to be moving in lockstep with equities and their role as parachutes are holed. Indeed, some of the initial moves lower in say the Japanese Yen, Gold and Bitcoin are a necessity of profit realisation to finance positioning in the heavy populated A.I. trades for example. In historical cases when not knowing what to buy, US Treasuries have nearly always provided a comfortable strip where wealth can be landed, nurtured and kept oven-ready until as such times the investor landscape becomes more favourable. But with inflation stalking every part of the US economy now, and the recent baring of hawkish fangs from Federal Reserve Board members and of course, the enormous US national debt to service, owning a piece of financial Americana at present does not seem remotely safe. Nor in fact, does it feel that way for our market at present.
Overnight Pricing
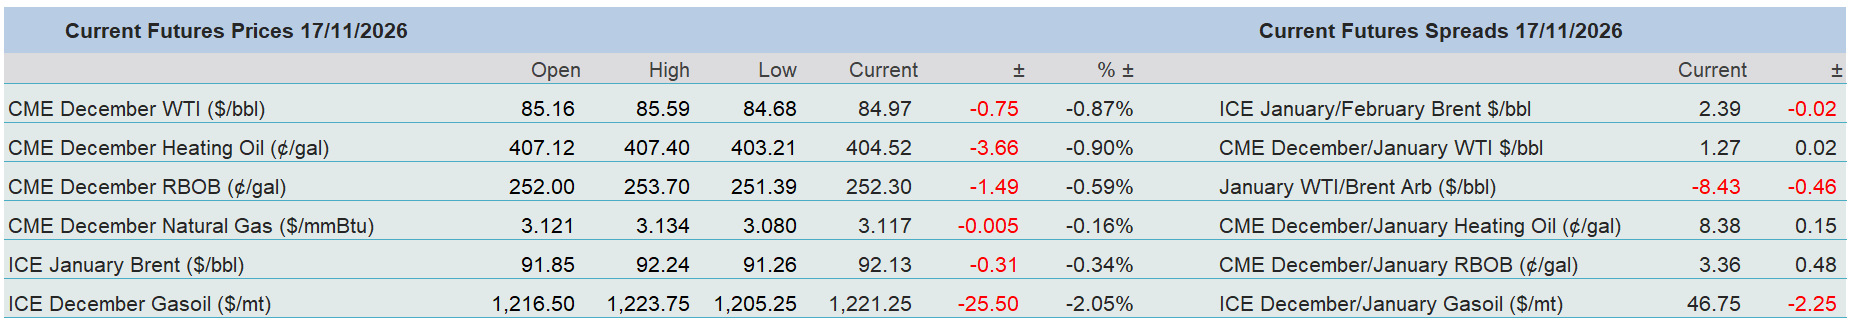
17 Nov 2026
