Mid-Terms on the Mind
In a worrying sign that the efforts to keep Houthi activity at bay by Saudi Arabia are failing, the United States has ordered the return home of some diplomats, and their families should leave the Kingdom and indeed other regional missions. Diplomatic edicts are ordinarily precursors to greater danger from military activity and given the targeting of Saudi oil facilities and shipping by the Iranian aligned rebels, the market then conceives attacks on the likes of Yanbu, its feeding pipelines and indeed the ships that take oil forward into the globe will be subject to greater repetition from Houthi aggression.
If there now feels a greater sense of urgency or that some sort of nexus is upon us, it might just be the US Mid-Term elections. The vote on the 3rd of November creeps ever nearer and the activity of Iran and its successful proxy in Yemen are increasing commensurately to the election’s importance. There is a post on ‘X’, as seen on ‘Bloomberg’, from the IRGC that it had struck four “violating” tankers in the northern Persian Gulf. Yesterday, three other vessels hit sea mines West of the Strait of Hormuz and Iran is now targeting shipping as far out as those in the Gulf of Oman.
Jump two thousand miles north and the same sense of revving political engines is observed. Overnight there was a fresh barrage of Russian missiles onto Kyiv the day after it was announced that China would host the US and Russia to discuss the end of the Ukraine war. How this must feel to the increasingly isolated Ukraine is beyond disappointment, but Donald Trump must be seen to be putting action to words in his campaign to bring oil prices down. The price of oil has become leverage to not only the Democratic opposition within the United States but also to those that are traditionally international antagonists. This is why the US President is concerning himself with the machinations of how red diesel is taxed and now offering out a third of the 1-million-barrel US emergency heating oil reserve, the size of which can only be described as risible.
Too much gas from the White House is not the right type for Europe
It seems quite the drastic thought process, in among many these days, to wish for the super El Niño to unleash all its power into Europe as the winter approaches. Well, from those that must supply gas that is. The flood damage would be horrendous, however, the prospect lays before many folks to choose whether they would like their local river as accompaniment to their winter TV watching or to sit there hunkered down in layers because the price of heating means all thermostats will be turned lower or indeed switched off.
El Niño is once again threatening to strengthen the weather patterns into the westerly Jet Stream and bring very much wetter weather to north-west Europe, the UK and Scandinavia, but importantly milder temperatures. Such prospective warmer climes would bring a drawdown in energy use and with the wind environment increased, the generation from wind farms might actually earn their keep given their predilection to ruin a perfectly good landscape with unturning sails in benign wind conditions. Wind generation is fraught with competing metrics and opinion but given the ‘Met Office’ data in the UK, as read in the ‘Telegraph’ opines that a “global stilling” is being witnessed in average wind speeds, any increase in wind turbine activity is welcomed.
This of course foregrounds the issue facing Europe over the state of gas reserves and what demand might look like in the months that end 2026 and start 2027. Across the European Union, gas inventories are filled to around 74 percent of capacity. Not only does this represent multi-year lows but it is the lowest on record for this time of year. The historical norm would see tanks being filled to the tune of 10 percent more as autumn arrives with legislated higher storage being achieved as term and spot deals are exercised in delivery. According to ‘LSEG’ analysis, typically, storage provides 25-30 percent of winter gas consumed in the EU, leaving the bloc heavily dependent on pipeline supplies and LNG. If that type of pull on gas is repeated, then tanks only half-filled as a maximum are a very sobering reality. This is a far cry from the EU security standard requiring individual nation gas storage to reach 90 percent capacity before winter, although there is a built-in caveat allowing for only 80 percent when difficult market conditions or when technical constraints arise.
Dutch Title Transfer Facility, or TTF commonly, the most liquid wholesale natural gas price benchmark for Europe is seeing its futures price charging into levels not seen since the Russian invasion of Ukraine. At the end of August, front month TTF was trading at €70/MWh, much higher than anything witnessed in 3 and a half years, but the latest round of storage numbers has brought about another bout of fear buying and this week the price nearly achieved €90/MWh, lancing into something not seen since December22. While not entirely to blame, the short sharp shocks to gas supply caused by the Iranian war had many making gas purchase decisions based around believing that the conflict would also be a short sharp shock. Urgency has replaced price but Europe faces stiff competition from Asian buyers of LNG and no matter that the United States, Canada and Nigeria have increased exports of the liquefied form of gas, the large sources of Middle East LNG supply from Qatar and the United Arab Emirates remains stubbornly locked behind Hormuz doors which ordinarily service, along with other sources, the Asian demand.
The price rises and threat to inflation are self-explanatory in Europe. Costs to the wellbeing of both civilians and industry come at a heightened time of political tension and civil unrest. Eurozone inflation accelerated to 3.3 percent in August, while energy prices rose 14.3 percent year-on-year. Buying spot market deliveries into an already rallying price to service depleted storage will not only impact the costs to business and households, but it will also force the ECB to maintain its likely forward path of ‘higher for longer’ interest rates. Unrest in France which has been echoed in Spain, Italy, Portugal and Belgium is spurred by many issues but many protestors express unhappiness about rising living costs, including fuel prices. Europe is once again paying the immediate price of the folly of Hormuz and its leaders will not risk disgrace by going cap-in-hand to Russia for a gas handout. Blow your winds El Niño, blow your winds.
Overnight Pricing
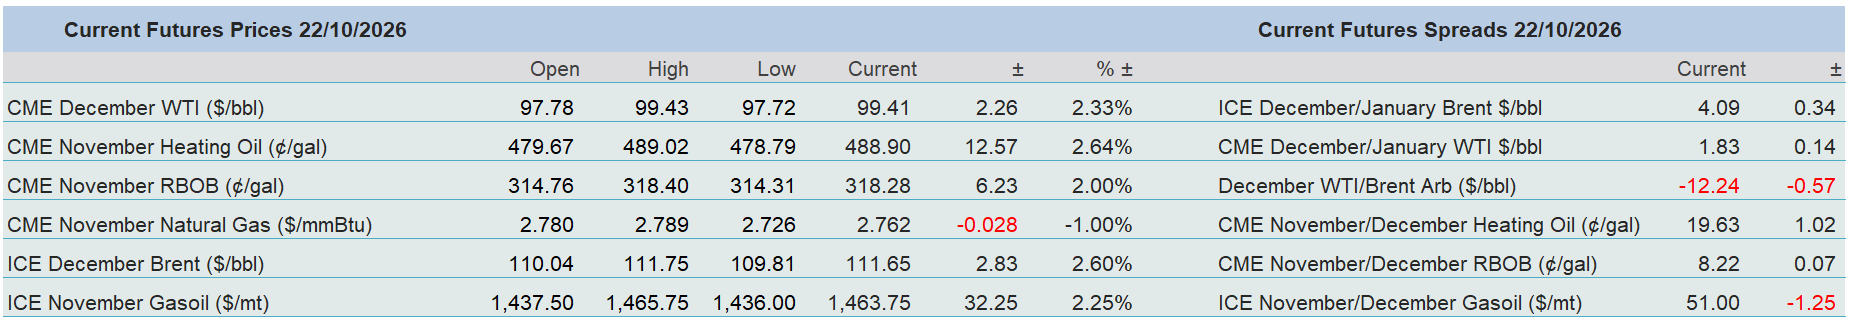
22 Oct 2026
