Misplaced Mid-week Optimism
Heads were spinning, and eyes were rolling last week. It was a cumbersome task to follow, minute by minute, the events that shaped the thinking and views of the investment fraternity. Markets were volatile and, at times, even violent. Now that the dust has settled on the developments of a turbulent week, the key takeaways, admittedly and almost obviously arbitrary, are as follows: investors sent a strong message to all involved: end the conflicts; they do no good to anybody. It also became more apparent than before that US diplomatic prowess is more pronounced in rhetoric than in action.
The week in terms of performance was as follows: global equities, in general, were stable. They were invaluably assisted by the ongoing AI craze, as the Nasdaq Composite Index made a fresh all-time high early in the week and ultimately gained 2%. The dollar strengthened and bond yields skyrocketed. Oil, with the exception of Brent, lost value, with products, particularly Heating Oil, going on a rollercoaster ride.
Deciphering the consequences of major foreign-policy intentions is a burdensome adventure. The United Nations General Assembly provided the backdrop to bilateral and multilateral talks and agreements, to which the United States, as usual, was a party. The Iranian and Ukrainian crises were complemented by the US-Greenland-Denmark Agreement, the appearance of the interim Venezuelan president in New York and the Trump-Xi summit.
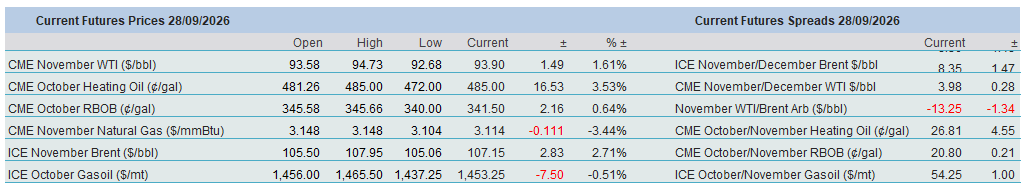
One of the two salient issues is the ongoing Iranian war. In the run-up to the Assembly, there was a discernible morale boost among politicians and investors, with great strides towards some form of rapprochement expected, bringing auspicious repercussions for the region and the global economy. This tangible optimism pushed the price of Brent close to $97 by Wednesday. Yet the upbeat mood proved ephemeral. A combative Trump speech and Iran’s insistence on lifting the US naval blockade as a precondition for allowing traffic through the Strait contributed to a sharp U-turn, sending the European benchmark above $108. The week ended in an apparent stalemate, with Iran firmly putting the ball in the US court to end the confrontation. Shin-kicking and arm-twisting are likely features of closed-door talks, which reportedly included a proposal from Iran for a phased reopening of the vital waterway, flatly refused by the US President over the weekend. Hence the $3 rally this morning.
The stand-off and the absence of a reliable timeline helped the European crude oil marker post almost unprecedented gains over its US peer, in a clear sign of how market players are evaluating the current prospects. Brent settled $12/bbl above WTI, adding another $1 to the premium overnight, and was also helped by perennial Houthi attacks on Saudi export ports and infrastructure, and not even significantly increased oil loading around Hormuz was able to alleviate Middle East anxiety. Apart from the Brent strength, the WTI relative weakness originates from expectations of lower US refinery runs, should the diesel export ban be imposed.
There were no direct or indirect meetings about the Ukrainian conflict in New York; however, in his speech, the Ukrainian President called for intensifying pressure on Russia while defending his country’s warfare against Russian oil infrastructure, although he emphasised that reciprocal de-escalation measures could lead to a halt in attacks. Curiously, but not surprisingly, the US President squarely put the blame on President Zelenskyy for untamed US diesel prices and has been putting pressure on Ukraine, and only on Ukraine, to stop hostilities. The domestic diesel picture is so dire that the guessing game over whether an export ban will be introduced sent the CME Heating Oil contract on a whirlwind trajectory. At one point, the ICE Gasoil contract traded above Heating Oil, while the Heat/WTI crack spread suffered a $8 loss over the week.
The Venezuelan interim president, seven years after warning of the US seizing Venezuela’s resources, returned to the very same podium to thank the US for doing so, while promising democratic elections without elaborating. Worth mentioning is the US-Greenland-Denmark Agreement, which allows the US to establish a military presence on the strategic island while unconditionally preserving Denmark’s sovereignty and Greenland’s right to self-determination. It seems to be a major climbdown, concession or even capitulation from the original US goal of taking over Greenland. While a US-China summit is usually on the front pages of newspapers, last week’s affair was rather muted, focusing more on formality than substance. The most pivotal achievement was the extension of the trade truce until January 10.
It was a tempestuous week in a turbulent world. Unpredictable and impulsive foreign and domestic policies in the world’s mightiest economic and military power are never a sign of trust and credibility. The impact of the geopolitical upheavals is a testament to this. Energy is expensive, supply chains are disrupted, and trade suffers. Put them into a formula, and you will have high inflation and inflation expectations. Extrapolate the result, and you will see that central banks have no choice but to raise interest rates as bond yields rise unstoppably.
And there is no weapon in the US Treasury’s arsenal to stop the rot. The yen intervention, which aimed to prevent Japan from selling US Treasuries, made little impact. The Treasury’s attempt to buy government bonds in the value of a few billion dollars in a market worth $30 trillion is also a futile exercise. The Treasury Secretary, Scott Bessent, warned currency traders that ‘I am the house now. You can bet against me if you want.’ Well, he did exactly that, quite successfully, 34 years ago, while working for George Soros’s Quantum Fund, which broke the Bank of England. The house always wins in any of Mr Trump’s casinos. Financial markets provide a much more level playing field. After last week, conviction is growing that the most potent, well, the only tool in the shed to provide a solid economic background and ensure that the house wins is to end conflicts. It is only fitting to finish this piece by citing a sentence from the US President’s UNGA speech: ‘to the victor belong the spoils’. The US might not be it.
Overnight Pricing
28 Sep 2026
