Prepare for a Different Type of Standoff
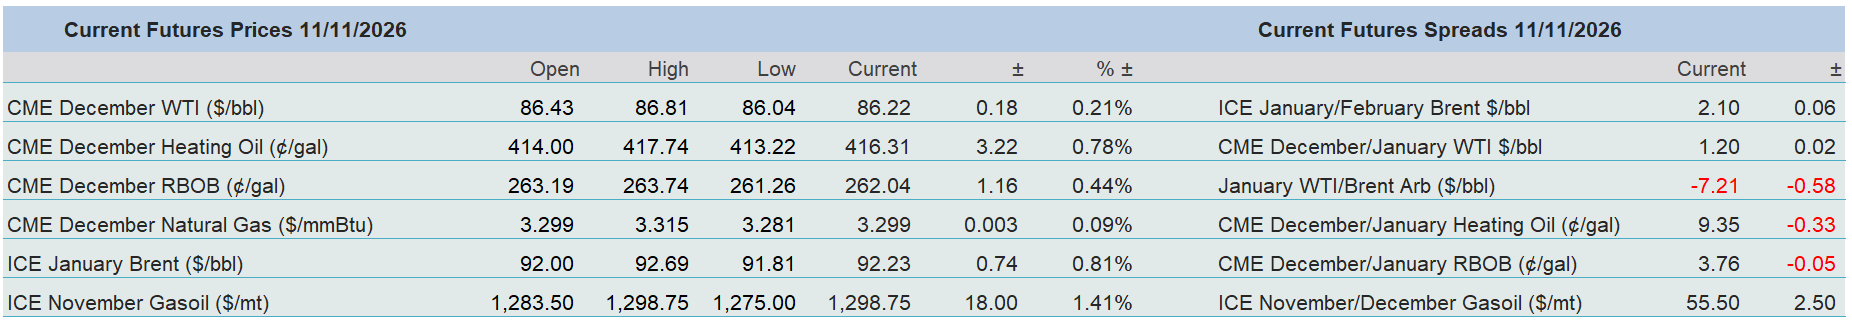
Oil prices find themselves at something of fulcrum here. There has been a 50 percent retracement of the gains made from the highs of conflagration fear, and indeed, in the case of RBOB, there is nearly a complete surrender of the rally. The trouble being, we now have entered a different miasma created by our protagonists. The conflict has sentimentally journeyed from what might next be bombed and the sort of retaliation it would induce, to what the nuts and bolts of a peace deal looks like and if Iran will accept it. The conciliatory tone being adopted by the US President and his seeming rubber stamping of the Qatari initiative to plot some sort of peace accord would have that this war is on the way to being over. But by any standard there has been a rebuttal from Tehran. Iran’s Foreign Ministry spoke yesterday on only signing a peace deal that is in Iran’s interest. But heftier words came from Iran’s Supreme National Security Council chief Mohsen Rezaei, and as reported on Tasnim, describing US claims about continuing negotiations or a planned meeting in Qatar as "complete lies." Boy, did the US President pick the wrong adversary to go to war with and transactionally joust.
Oil is not the only price accelerator
We enjoy the wherewithal, and simultaneously launch barbs, when watching the ‘all in’ and ‘all out’ practices of markets these days. A notion is set in motion and cues the thundering herd to stampede all that makes for logic and data. There is an audible sigh of relief emanating from the wider suite as its community believes that the influence of oil prices on inflation has suddenly exited stage left. The economic input of crude oil is a fundamental activist in stirring price rises which are felt in direct terms by customers on the forecourt as they fill their cars, and indirectly in the costs to businesses at large. When oil prices impinge on the habits of everyday folk, it is seen as a slight at their personal freedom, particularly in the United States, and one only need read around the edges of the Midterm election autopsies to find that the ‘blue wave’ which dislodged the Republican party was laid squarely at the foot of the Iran war and the effect it had on fuel prices, and indeed, the emotive feeling that social mobility had become hampered.
Yesterday’s US CPI reading showing acceleration of 0.4 percent month-on-month outlines the progress and outcome of long-term inflation. The present lower state of crude oil prices will be of little consequence. As a rule of thumb, it is accepted that for every $10/barrel move in crude there is a 25c/gallon equivalent shift in gasoline prices. Would that refineries were blessed with such immediacy. There is an interminable gap in how lower crude prices might be reflected in retail gasoline and diesel prices. Whenever anyone wishes to capture the meaning of the ‘rocket and feather effect’, using the price action of refined fuels is peerless. It is not just how the feedstock being currently processed was probably purchased $10 or $20/barrel higher than current levels attest to, it is the myriads of other influencers contriving to keep pump prices from falling as fast as the underlying base material from which they are made. Notwithstanding the actual refining margin, consideration must be given to shipping and transport costs, retail and wholesale mark ups and of course, everyone’s pet hate, taxes. Operational cause and cost effect indeed. Getting refined fuels to pipe through such price escalators takes months, no matter what futures markets, both in crudes and in products might represent. The Trump called “little excursion” is now nine-months old and whatever inflation there has been is now baked into supply chains, forward business contracts and probably wages. The inflationary effect of oil and energy prices will continue to ripple through any measure of inflation from CPI, PPI or CPE.
Oil does not stand in isolation; it being blamed for inflation does not add up when considering core inflation readings. Core inflation strips out the influential and unpredictable prices of energy and food in the economies of the EU, the UK and the US. They are 2.5, 2.8 and 2.6 percent respectively and well above the 2 percent targets to which we are assured all of these major economies view as the optimal level. There are of course indirect consequences of oil inflation, but the drivers of core inflation such as the manufacturing industries of cars, household goods and clothing along with those in services such as housing, health and entertainment portray a deep-seated chorus of price escalation that will continue to need attention from central banks charged with keeping order in economies.
The US President’s insistence on making trade war with almost every country means that tariff costs are finding their way into price chains and until such a time as protectionist policies cease, inflation will always have a helping hand higher. Staying with Trump’s upsetting of the geopolitical apple cart, his country is now an unreliable ally which has seen an inordinate increase in military spending, particularly in Europe with the Stockholm International Peace Research Institute earlier this year showing that World military expenditure reached $2.887 trillion in 2025, an increase of 2.9 percent in real terms over 2024. Military spending declined in the United States but rose by 14 percent in Europe (Germany saw a massive spike of 24 percent) and by 8.1 percent in Asia and Oceania. While initially good for GDP readings, elongated spending on arms stretches internal manufacturing capabilities and is thus inflationary.
This does not even take into account the demand from the technology sector. There is unprecedented spending on the A.I. buildout with investment in data centres, chips, processors, specialised software and the hardscape of electricity grids and construction creating its own particular brand of bottleneck. Through the prism of oil prices, the magnificent and intrepid brothers and sisters of investment tourism are kicking the can of inflation around as if it is a beaten foe. However, the oil portion of the inflation pie, while very important, is not the only slice in town, and not only is it premature to believe inflation will suddenly cool, but it is also premature to think the Middle East and other oil-effecting, inflationary wars are likewise cowed.
Overnight Pricing
11 Nov 2026
