Running Out of Reasons Not to Rally
Despite the waiving of Russian sanctions and the waving off of a large part of global goodwill, the US decision has not had the sentimental follow through in easing oil prices as is designed by the controversy. Whatever might flow from the Black Sea or Northern Sea Route (NSR) will be paltry in numerical barrels and will not help against the drawdown in oil inventories of the US or elsewhere any time soon. So says a ‘Reuters’ poll this morning predicting mild US draws across crude, distillate and gasoline this week, and so says the approaching expiration of the CME M1/M2 WTI futures spread with its $5/barrel backwardation that screams tightness in nearby crude barrels. Downside risks are starting to be limited as the situation worsens in the Middle East. Notwithstanding, according to ‘Kpler’, the 18 attacks on shipping in the last 2 weeks, the Houthi attacks into Saudi are bearing more fruit and having influence on the daily lives of the Kingdom’s citizens. Within the last 48 hours, attacks have been seen on the Shaybah oilfield and the Yanbu Aramco facility and last night there are reports of an attack on King Khalid International Airport, with the volume of flights in and out of Riyadh’s airports much reduced due to aerial risk. The Future Investment Initiative conference (FII), termed ‘Davos in the Desert’ will now not be held ‘in person’ and some reports from attendees being told it is postponed until next year. The oil market is now starting to experience and express the value of chokepoints which do not see a cure on the balance of the 2026 horizon.
Desperate times and the consequence of desperate measures
Last week saw the 100th anniversary of the creation of A.A. Milne’s ‘Winnie-the-Pooh’. The anthropomorphic teddy bear is known as a bear “of very little brain.” However, some of Pooh’s simplistic sagacity matched anything in the Bible or of Greek philosophers’ fame. “What day is it today?” asked Pooh. “It’s today,” answered Piglet. “That’s my favourite day,” concludes Winnie-the-Pooh. Indeed, today is the only day traders can react to, and today, in the perpetual sense, changes as much as any of the cartoonish characters in charge of our world allow. The famous quirk or trait of the fictional teddy bear was to get himself stuck in tight spots and the following writings would be on how his extrication would come about. Does this ring any bells yet?
We, along with others, have noted that the power of Mr Trump’s words to talk oil prices down is eroding at a rapid rate, action must now supplant words. If any citizen of the world held onto any vestige of belief the US President had any concern for what might ail the global common good, it has been snuffed by the latest move in which the White House cosies up to the Kremlin. Arguing on Friday that “in the national interests of the United States,” Trump signed an executive order, waiving key sanctions and tariffs formed in the Graham Act, the bill designed to pressure Russia into seeking peace and desist in its aggression in Ukraine.
Whatever legal nightmare this creates for US Customs and those enforcing Russian restrictions matter not a jot, something Russian this way comes. And no matter how paltry the amount of oil. In fact, the agreement for Russia to supply the global market with 4.8 million metric tons of diesel, is the equivalent of about ten days of US domestic demand, or about a single day of global demand and is greeted with scorn. We noted this yesterday, but it is worth repetition, “It does not even touch the sides – it is very, very small,” the former head of the IEA’s oil industry and markets division, told ‘CNBC’ on Monday. However, if it lasts, as the US President said there will be a 6-week review, our market might consider it being the thin end of an oil delivery wedge. Such a move can only alienate Europe yet again. The process of weaning the Old Continent from Russian energy has been an expensive and divisive one, this unilateral dismantling of sanctions by Washington will not be without wider political consequence. It may even add to the unrest being seen in the European mainland as nationalism gains favour and with it a possible easing of antipathy toward Vladamir Putin and yet even more sorrow for Ukraine.
The Trump move, and many unforeseen facets of fallout, is not lost on Ukraine President Volodymyr Zelenskyy. Speaking with reporters he rhetorically asked what will happen after sanctions are lifted on oil? He speculated that gas supplies would then be freed of trade limits, then chemicals, then the very rich sanctioned individuals who would be allowed financial impunity and what of the most powerful of tool, the global clearing system. He continued in worrying speculation on how any quarter given to Russia might eventually lead to a cutting off of Ukraine from US military intelligence and technology. The defensive and offensive capabilities of Ukraine forces showed their vulnerability last week when their access to internet connections was limited by Starlink and the use of Starshield, the system used to launch missiles or drones and guide them.
Winnie-the-Pooh gets stuck in narrow doorways and ‘hunny’ jars, the US President is stuck in the Strait of Hormuz. His thrashing around to appease domestic oil prices and win votes on November 3rd has now inextricably linked two wars and the collateral is Ukraine. Such sacrifice will not remain in isolation. The prospect of a defeated Ukraine is now on the ‘gaming’ of European strategists. The only answer will be a quickening in the re-arming currently underway across the continent and massive costs at the expense of the many unforeseen social programmes and domestic investment. Inflation and interest rates will now not come down, and the sorry sights of unrest seen in France and beyond will become the everyday. ‘Today’ really is the only day to be concerned with, because each trading 24-hours has now been given an exponential potential to cough up even more unknowns.
Overnight Pricing
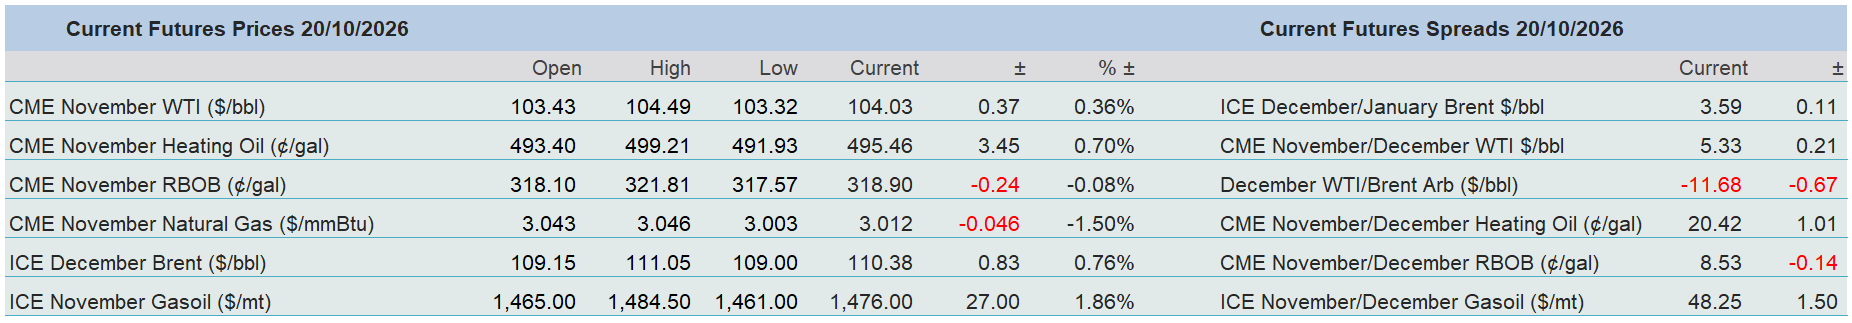
20 Oct 2026
