Shifts Happen
Genuine hopes of the reopening of the Strait of Hormuz emerged in the middle of June. After all, there was an understanding between the US and Iran about the concessions the parties were willing to make in order to lay the groundwork for further and more substantial negotiations. As it turns out, the light was not the end of the tunnel, but an express train coming from the opposite direction, leading to a head-on collision with tangibly rising optimism. The mood has changed, and as the conflict escalated and even expanded into the Red Sea, oil prices started to rise. The latest nudge higher came as Saudi Arabia was forced to temporarily shut down its East-West pipeline following Houthi attacks, jeopardising 4 mbpd of crude oil exports.
An additional boost arrived as the planned talks between Iran and the Gulf states were postponed, possibly due to the aforementioned strike on the Saudi pipeline. Friday’s peaks were seriously tested before two claims from the US President provided an excuse to bank some profits. Mr Trump asserted, once again, that Iran badly wants to make a deal and that Ukraine and Russia had agreed to halt their strikes on each other’s energy installations. His words, it appears, still carry some weight.
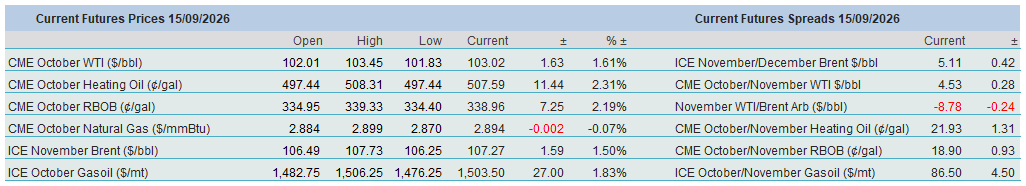
Although Brent settled some way below the $110/bbl peak, persistent tension in the Red Sea and non-existent traffic through the Strait are supporting the oil complex once again this morning. US retail diesel prices are at a record high, reaching $6.23/gallon yesterday. Inflation is elevated, and bond yields are on the ascent. This week’s Fed meeting will set the central bank’s chair on a collision course with the US President if FOMC voting members decide to increase interest rates, as widely expected. The US Administration’s narrative is in stark contrast to its actions and to reality. The collective impact of military and trade wars is taking its toll on the economy and its prospects, and, as President Trump’s foretold last week, conditions will not improve until after the midterm elections. Investor and consumer sentiment has taken a turn for the worse.
Healthy Financial Appetite for Oil
The price speaks for itself. Apart from Friday’s correction, it rose every single day last week and continues to climb at the start of this week. The reason is well-publicised, advertised and analysed. Not only did the Middle East conflict escalate, but it also expanded as the Houthis, now very conspicuously, opened a new front in the war, severely impeding Saudi Arabia’s ability to successfully circumvent the traditional oil export route via the now notorious Strait of Hormuz. The US narrative about controlling the Strait is akin to the former Iraqi information minister’s claims during the second Gulf War that his army was defeating US troops, as US tanks were literally lurking in the background. The latest bout of escalation has sent physical prices higher. Physical markets, particularly for products rather than crude oil, are tight, as reflected in eye-watering refining margins.
Since financial players have access, more or less, to the same amount and quality of information as physical traders, futures outright prices are also on the rise, and the structure of the five major contracts is one of steep backwardation. Elevated upside risk is mirrored in the latest Commitment of Traders reports from the CFTC and ICE, which cover the period up to the previous Tuesday, September 8. Since prices have risen in the following five trading sessions, the picture will be even more upbeat when the next sets of data are published at the end of this week.
Looking at the figures from the recent past, it seems that early July marked the point when the market was most optimistic about the conflict ending in the foreseeable future. In a way, this is understandable, since it was just two weeks after the announcement of the Memorandum of Understanding between the US and Iran, which envisaged at least the temporary re-opening of the pivotal waterway. As it dawned on market players that the agreement was not worth the paper it was written on, and the risk of further supply and export disruption remained elevated, position adjustments got under way in earnest.
Total assets under management, the product of net speculative length (NSL) and prices, tripled from $22 billion to $69 billion. Curiously, crude oil was leading the way higher. Combined WTI and Brent NSL rose from 90 million bbls at the beginning of July to 406 million bbls last week. Assets in the two major crude oil contracts increased almost sevenfold, from $6 billion to $39 billion. Since the major price driver is the Middle East and, to a certain extent, the Russian crisis, the impact on Brent has been more profound. NSL rose by 250 million bbls, versus an increase of 66 million bbls in WTI futures and options. It is also noteworthy that the long/short ratio in the European crude oil benchmark reached 3.6 last week. The net NSL of 265 million bbls comprised gross length increasing from 281 million bbls in July to 369 million bbls last week, while gross shorts cut their exposure from 266 million bbls to 104 million bbls. In other words, a significant amount of fresh money landed in Brent, a vote of confidence in prolonged price strength.
NSL in Heating Oil almost quadrupled from 4.8 million bbls to 16 million bbls between the beginning of July and September, while NSL in RBOB rose from 72 million bbls to 92 million bbls. Over in Europe, Gasoil NSL jumped from 6.9 million tonnes to 9.3 million tonnes. Its long/short ratio is even more impressive than that of Brent. At 5.2, it reflects an unequivocal view of a very tight physical market.
The three product contracts were responsible for a mere $13 billion inflow out of the collective $47 billion increase in AUM. Consequently, the share of the two crude oil contracts in the total speculative pie swelled from 28% at the beginning of July to 57% last week. Given the relentless rise in refining margins, this might come as a surprise; however, it is because, in an uptrend, financial investors predominantly favour the most liquid contracts, and those are the crude oil futures. If there is any conclusion to be drawn, it is that geopolitics is at the forefront of money managers’ minds, and presently the outlook is ominous, which is bullish for oil.
Overnight Pricing
15 Sep 2026
