A Sombre Day, No Lessons Learnt
The US and most of the world will remember today all those who lost their lives during the atrocious terrorist attacks on the Twin Towers and the Pentagon 25 years ago. Yet the moral of these terrible events seems to be fading from memory. Ideological differences and historical grievances, not to mention territorial aspirations, are not resolved behind closed doors and through negotiations, but by rattling sabres at the actual or perceived enemy. The two contemporary examples are the Ukrainian conflict and the Gulf war, and neither shows any signs of de-escalation.
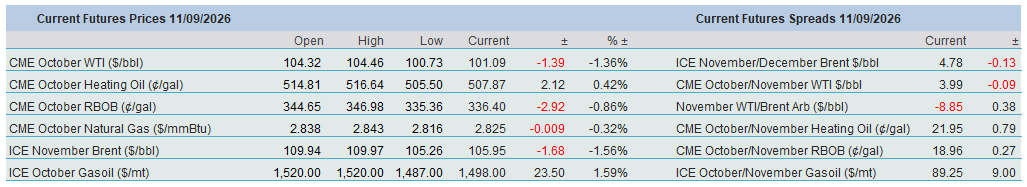
The reciprocal attacks on oil installations between Russia and Ukraine have not eased, which is echoed in the decline in Russian oil production. August saw the ninth successive monthly decline, according to the independent consultants used by OPEC. In the Middle East, a truce remains probably more elusive than ever, as ships in the Persian Gulf are being attacked more frequently than at any time since February. In western Saudi Arabia, the Houthis are reportedly advancing along the Yemeni coast and have taken control of the port of Mocha, presenting a clear and present danger to Saudi oil shipments via the Bab el-Mandeb Strait. Brent reached its strongest level since May, while Heating Oil sliced through the highest point of the conflict like a hot knife through butter.
This morning, investors are reacting to a report by the Financial Times about a meeting between Iran and Gulf nations in a renewed attempt to reach a temporary deal allowing ships to pass through the Strait. It would probably be unwise to hold one’s breath.
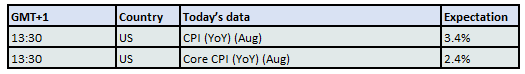
The economic impact is plain for every investor to see. Bond yields are rising, ignoring the ill-fated intervention by the US Treasury on Wednesday to continue its bond-buying programme. The ECB raised the cost of borrowing, and further hikes are plausible. Costly energy prices will give the Fed a migraine-type headache next week, while US producer prices jumped 5.4% in August. Today, it is the turn of consumer prices. The US administration appears reluctant to take steps towards easing inflationary pressure. Consumers and investors are delivering their harsh verdict, and a reversal does not look imminent. Could we expect soothing social media posts or announcements from the White House shortly? Maybe.
OPEC Remains Convinced of Persistent Supply Deficit
To conclude that the EIA and OPEC sing from the same hymn sheet, that they share each other’s views on supply and, more importantly, demand developments, would be a brazen and misleading statement. The differences are jaw-dropping. The former remains more than sanguine about global oil consumption this year and next. In its latest Monthly Oil Market Report, OPEC revised both its 2026 and 2027 demand estimates upwards. The main reason is probably the retrospective 300,000 bpd improvement in last year’s projection. However, this does not change the fact that, as opposed to the EIA’s estimate of a contraction of 1.69 mbpd this year, OPEC envisages growth of 330,000 bpd. The difference between the two absolute numbers is 3.24 mbpd – 102.59 mbpd for the EIA and 105.83 mbpd for OPEC. Analysts in Vienna expect global stocks to plummet at a rate of 3.85 mbpd this year, while experts in Washington, DC, put the same figure at 1.96 mbpd.
The schism widens next year to 5 mbpd. The EIA’s stock build of 4.89 mbpd is juxtaposed with OPEC’s average drawdown of 100,000 bpd in worldwide oil inventories. Both expect global oil demand to expand by 2.38 mbpd, so the difference comes from the supply side. Supply will grow by 9.13 mbpd, the EIA reckons (4.08 mbpd non-DoC and 5.15 mbpd DoC), versus 5.98 mbpd (630,000 bpd non-DoC and 5.35 mbpd DoC). Full disclosure: the latter is our estimate. Anyway, to cut a long story short, these massive gaps will result in shockingly divergent OECD stock estimates for 2027. According to the latest EIA figures, OECD stocks will stand at 3.020 billion bbls at year-end, against OPEC’s prognosis of 2.495 billion bbls.
As laid out above, the producer group believes that the tight oil balance will not evaporate as quickly as the EIA forecasts. This stubborn view is the result of healthy oil demand, which does not appear to be meaningfully affected by elevated oil prices or diminished supply, precipitated by the Persian Gulf conflict. The war in and around this critical oil-producing region has had a tangible impact on the group’s output level in general, and on Persian Gulf producers, chief among them Saudi Arabia, in particular.
The collective output of the original producer group, excluding the associated members, fell from 28.65 mbpd in February this year to 18.87 mbpd by May. This was when the bottom was found, at least for now, and a pedestrian recovery got under way. The latest figure shows that the group produced 24.801 mbpd in August. It is a decent bounce from the trough, yet still significantly below the pre-conflict level. The group’s dominance of the supply market has understandably suffered. Its share of global production, at 35%-36% in February, retreated to 27% by May and stood at 33% last month. Logic dictates that this would entail a significant loss of revenue. However, this has not been the case, as the financial impact of falling output has been partially offset by rising prices. A rudimentary calculation, the product of monthly output and the price of OPEC production, suggests that daily petrodollar revenue actually rose from $1.95 billion in February to $2.17 billion in May and was still at $2.08 billion in August.
Yet there has been suffering, and Persian Gulf oil producers, namely OPEC heavyweight Saudi Arabia, have borne the brunt of it. The Kingdom’s production between February and August dived by almost 2.9 mbpd, or 28%, compared with 4.5 mbpd, or 16%, for the entire group. It has not exactly been losing money hand over fist; however, its average daily income declined from $686 million prior to the crisis to $629 million. This equates to a fall of 8%, while the income of the entire group actually rose 7%. This is a rather trivial phenomenon: geographical proximity makes Gulf producers disturbingly exposed to the conflict, as manifested by frequent Iranian hostility towards oil infrastructure and shipping lanes in the region. Notwithstanding rising prices, the war is causing material, financial and economic harm to regional oil producers, who, no doubt, are doing whatever they can to bring the curtain down on this unnecessary conflagration, so far unsuccessfully.
Overnight Pricing
11 Sep 2026
