Stoicism is Required
Given the newly found love affair between oil prices and bond yields, it is self-evident, almost axiomatic, that borrowing is becoming ever more expensive. Although US Treasury yields pulled back from recent highs after decent demand at the latest 30-year bond auction, fears of inflationary pressure and competition between sovereign and corporate debt will likely keep borrowing costs elevated.
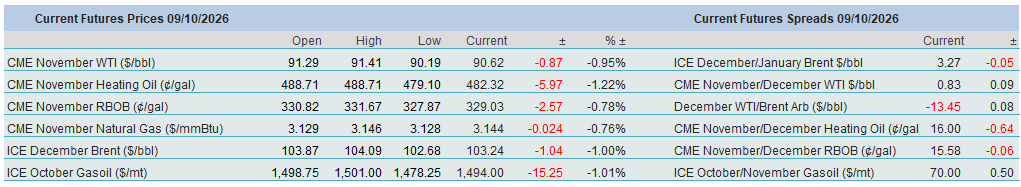
These inflationary fears, as mentioned, are chiefly driven by stubbornly high oil prices following Iran’s escalation of attacks on tankers travelling through the Strait of Hormuz. At the same time, Houthi strikes on Saudi Arabia continue unabated. According to Kpler, oil flows through the Persian Gulf chokepoint, which stood at 15 mbpd two weeks ago, fell to 4 mbpd on Tuesday. It is hardly surprising, then, that oil prices recorded decent gains yesterday, also supported by production shut-ins in the US Gulf due to Hurricane Isaias.
The sting was nonetheless taken out of the rally following yet another confusing and contradictory social media post from the US President. The Atlantic magazine reported that the US was considering striking Iran before the midterm elections. President Trump rejected the report, however, saying that no such attacks would take place before November 3 because of “productive discussions”. Who is to believe?
The oil fraternity is doing what seems only reasonable under the circumstances. It remains stoic and, in the absence of any reliable guidance, reacts to headlines as they emerge. There is a smorgasbord of questions about the outcome of the Iranian conflict, but few answers. One such question is this: if no US attacks on Iran are forthcoming in October, did the President hint at an attack after the midterm elections, and will he be able to launch one?
Peculiar US Midterm Elections
In Tuesday’s note, we were contemplating the possible impact of the US midterm elections, which are less than a month away. The conclusion was the most logical one: it is impossible to predict the outcome and, consequently, the reactions. Recent polls suggest, and admittedly, they can change on a whim, that the Democrats will regain a majority in the House of Representatives, while the Senate is on a knife edge; it could go either way. Should the Democrats come out on top in both chambers, the US President’s ability to implement legislation and exercise executive power would be materially constrained. However, he WILL remain the President, with significant unilateral powers. For one, he would still be the Commander-in-Chief.
The backdrop to the midterm elections is extraordinary, if this word has not lost its true meaning over the past 18 months. The incumbent party losing one or both chambers of Congress is no deus ex machina; history shows it is more plausible than not. However, in typical Trumpian fashion, it would be easy to argue, based on hard facts, that the Republicans genuinely deserve to remain at the helm of the US legislature until after the second Trump presidency ends.
The US economy is roaring. The Atlanta Fed estimates that third-quarter growth could be above 5%, exceeding Chinese growth. This, in itself, would be a remarkable feat. Stock markets are on steroids, notwithstanding yesterday’s pullback. The S&P 500 index is 30% higher than at the inauguration, while the Nasdaq Composite Index has rallied 38% since January 2025 and is making new all-time highs almost on a daily basis. The labour market is impressively resilient. Unemployment, while having ticked up from the March 2023 low of 3.4% to 4.2% last month, is historically at a more than acceptable level and causes no headache for the Fed. One of the administration’s campaign promises was to cut the massive trade deficit with trading partners. Although the dollar has strengthened of late, it is still significantly weaker than at the beginning of last year, in theory incentivising exports at the expense of imports (which it did not for various reasons, as the trade deficit remains substantial).
Yet, the outlook of the midterm elections is far from auspicious for the Republican Party, and the US President’s approval rating, a rather astonishing 32%, is at a record low. It seems that economic growth is akin to cholesterol: there is good growth and bad growth, much the same way as there is good cholesterol and bad cholesterol. And the US economy is apparently on the bad-growth trajectory. It is a self-inflicted wound, manifested in economic data, both soft and hard. US consumer sentiment, as measured by the University of Michigan, is at a four-month low. Its index dropped to 48.1 in September, almost matching the 50-year low. Bond yield rise is accelerating, and inflation refuses to come down; the 2% target is not attainable in the foreseeable future.
The economic data outlined above is the very definition of the contemporary fashionable phrase: affordability crisis. The two major elements, as pointed out in a Financial Times opinion piece, are energy and housing, with mortgage rates above 7%. The US-induced Iranian war constrains oil supply. Add to that the rising demand for electricity from data centres, and elevated inflationary pressure becomes conspicuous. The most efficient way to rein in price escalation is to slow the economy by making borrowing expensive.
This naturally leads to discontent and dissatisfaction as wage growth fails to keep pace with the increase in prices. The sound of frustration is becoming ever louder, even among hardcore MAGA supporters and those who voted for the President. Adding insult to injury is the widening wealth gap, which sees the top 1% of Americans hold over 30% of the nation’s wealth, compared with 2.5% held by the bottom 50%. As demagogic as it sounds, the medium-term economic implications are severe and real, as top earners spend a smaller percentage of their wealth than those at the bottom of the income distribution.
Transactional US policymaking is expected to continue in the event of a midterm outcome favourable to the Republicans. Supply-side economics will remain intact, and one will keep wondering how long the AI sector, on its own, will be able to support the equity market. A Democratic sweep would likely lead to gridlock in domestic policy, since the President would not lose control over the economy, but the legislative and institutional constraints would become more forceful. The same goes for foreign policy. The President would remain the head of the armed forces, but his authority would be restricted by Democratic oversight and Congress’s control of appropriations, funding and possible sanctions. The precise details are impossible to envisage, but an attempt by the Elephants to push through legislation and confirmations between November and January would be a dead cert.
Overnight Pricing
09 Oct 2026
