Stubborn Inflation, Unconvincing Peace Prospects
It is open to interpretation why the Fed did not touch interest rates just days before the midterm elections. What appears certain is that it will be tempted to raise them at the next FOMC meeting. The pivotal headline and core PCE readings came in line with expectations, at 3.6% and 3.1%, respectively. Robust growth of 3.4% in Q3 and resilient consumer spending also support an increase in borrowing costs, despite a wavering stock market, which fell yesterday as Alphabet lost $500 billion in market value in a single day. Amazon’s 4Q sales guidance also disappointed. The ECB took a leaf out of the Fed’s playbook and left rates unchanged yesterday, following the announcement of its President’s premature departure, despite eurozone inflation being at a three-year high, and the BoJ did the same overnight.
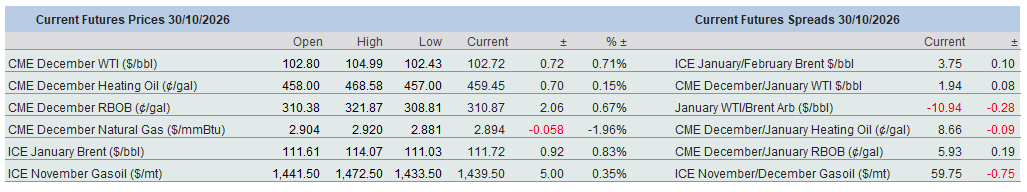
Although markets are moving with the headlines, there has been no material change in the geopolitical hotspots. Efforts to revive peace talks are only tentatively under way, while attacks on ships and refineries in the Middle East and on civilians in Ukraine continue, doing little to inspire confidence in the prospects for lasting ceasefires in the foreseeable future. Nonetheless, hope springs eternal, and the oil complex resumed its descent, led by Heating Oil. The crews of Russian diesel cargoes heading to the US are now shouting ‘land ahoy’, although it is worth noting that, according to Reuters, Moscow will extend its diesel export ban for the remainder of the year and fulfil its US obligations through a seemingly opaque quota system.
So, in essence, and notwithstanding yesterday’s market drivers, interest rates are likely to rise in the coming months; peace talks involving Iran and Ukraine remain elusive, and the diesel outlook has yet to brighten conclusively. To borrow a phrase recently used by my colleague, this dip will, in all likelihood, find grateful buyers, which is what we might already be observing this morning.
World Bank Group – Commodity Markets Outlook
With two conflicts raging in the vicinity of oil-producing and refining regions, and vital shipping routes directly affected, to say that the outlook for oil is ambivalent is an understatement. Widening the lens to account for the fact that it is not just energy but also other commodities and supply chains that are under strain makes the picture even more obscure and less clear-cut. Notwithstanding the ambiguity surrounding any attempt to form a decisive view of what lies ahead, the latest semi-annual Commodity Market Outlook by the World Bank Group (WBG), released on Wednesday, makes for intriguing reading.
Commodity markets have to contend with a confluence of shocks. In addition to the two most obvious ones, the war in the Middle East and Russia’s perpetual aggression against Ukraine, the WBG also identifies the El Niño phenomenon as a major driving force that will shape supply-demand balances and, consequently, prices across a smorgasbord of commodities, primarily agricultural products but also, to a lesser extent, energy.
In its Executive Summary, the WBG highlights the interconnectedness that characterises commodity markets. This relationship is not static; rather, it strengthens during periods of stress. The WBG observes that, under such circumstances, industrial metals transmit the greatest volatility to other commodity groups, including energy and agriculture. In its updated Outlook, the Bank projects moderate global economic growth, while investment in data centres and renewable energy is expected to remain robust. These projections assume no further escalation of tensions in the Middle East. They also rest on the premise that Russian oil exports will normalise next year. The impact of El Niño on agricultural commodities is assessed ‘with reference to previous particularly severe episodes’.
Agriculture: Food commodity prices are likely to increase by 10% in 2026, followed by a further 7% rise next year. Adverse weather and constraints on grain and oilseed shipments from the Black Sea are the main drivers. Rice supplies are set to decline as El Niño adversely affects production in Asia. Wheat prices are expected to rise in the coming years due to trade disruptions caused by geopolitical conflicts. Climate change, through the increased incidence of droughts, will add to the upward pressure on prices. Shipping constraints in the Black Sea are expected to ease next year. If they do not, food and grain prices could continue to rise beyond 2027. Export bans on food commodities and the increased use of biofuels could also help keep food prices elevated.
Metals and minerals: The WBG’s price index for metals and minerals is projected to rise by 25% this year, reaching a record annual average. Strong demand and supply constraints are behind the increase. Although a modest retreat is anticipated next year, the Bank’s metals and minerals price index is expected to remain significantly above its previous peak in 2021. Investment in electrification infrastructure, renewable energy and data centres, intensive users of base metals, will underpin healthy demand for these commodities. Iron ore prices, however, will come under pressure from weakness in construction and China’s steel sector. Potential upside risks include production disruptions and precautionary stockpiling, while the downside risk lies in unexpectedly sluggish economic growth.
Energy: The WBG estimates that global oil production will decline by 5.5 mbpd this year as a result of the conflict in the Middle East. Demand destruction is expected to offset around half of this shortfall. Nevertheless, depleted global oil inventories leave the world exposed to further supply shocks. Oil prices are expected to remain elevated in the near term, with Brent averaging $91/bbl this year, before retreating to $79/bbl in 2027 and $70/bbl in 2028 as the global market swings into surplus. Upside risks include renewed flare-ups in either conflict, a restrictive OPEC+ output policy and accelerated inventory drawdowns if production recovers more slowly than expected. Downside risks stem from an enforceable peace agreement in the Middle East, greater-than-anticipated demand weakness and robust supply growth from non-OPEC+ producers.
Understandably, particular attention is being paid to the natural gas market, where the global balance tightened in the second half of the year. Soaring prices curtailed consumption, which contracted in the first half of 2026. Meanwhile, regional supply disruptions originating in the Persian Gulf kept the supply deficit wide. The outlook remains tight, as the recovery of exports from the Gulf region is expected to be painfully slow.
The wars in the Middle East and Ukraine, combined with El Niño, are expected to drive global commodity prices up by 23% this year, predominantly due to a 32% surge in energy prices. The outlook for next year is mixed but relatively encouraging. Commodity prices are projected to decline by 7%, with oil and energy prices retreating, while food prices continue to rise. Global inflation may therefore moderate. However, this prognosis assumes that tensions in the geopolitical hotspots will not escalate. We dread to think of the consequences should these assumptions prove misplaced.
Overnight Pricing
30 Oct 2026
