The Supply and Demand Puzzle
In these ever-evolving markets, new information and data points were entered into the metaphorical crystal ball. The result was an equity sell-off in the first half of the week, followed by a decent recovery toward the end. Oil was broadly under pressure but bounced on Friday.
One of the main features of last week was how central banks dealt with inflation. The Fed and the Bank of Japan both raised interest rates. The Bank of England left rates unchanged but is apparently prepared to act should elevated consumer prices warrant it. As a result, the gap between bond yields, aka inflation indicators, and borrowing costs narrowed, or at least did not widen. If this mitigates inflationary pressure by acting as an impediment to aggregate consumer demand, oil consumption will also be affected.
And oil demand is, in fact, weakening, at least tentatively. In a tiny segment of the global market, France, a local industry association reported ‘unprecedented’ road-fuel demand destruction, OPIS reported. Product inventories in major hubs—the US, ARA and Singapore—swelled last week. A 13% rise in Chinese refined-product exports in August alleviated some of the tightness in Asia. The road back to $80/bbl in crude oil is clearly visible.
Maybe, but this road is paved with uncertainty and Truth Social posts. While the US President squarely blames Ukraine for skyrocketing diesel prices, he refuses to help one of his closest allies in the Middle East, Saudi Arabia, prevent Iranian proxies from damaging its pipelines and obstructing alternative shipping lanes, while reportedly holding a clandestine meeting with Houthi rebels. It is a nonchalant and damaging attitude less than two months before the midterm elections, one that foretells plausible flare-ups of the conflict in the Persian Gulf, with a potentially harmful impact on already-stuttering oil exports.
And flare-ups did occur over the weekend. Yemeni Houthis attacked the Saudi capital, Riyadh, and the city of Yanbu with missiles and drones. Yet, after a strong opening last night, oil prices have lost almost $4/bbl overnight. The sell-off is possibly due to resilient Saudi oil flows, which, according to JPMorgan, averaged 2.9 mbpd through the Strait of Hormuz in the last six days, up from 700,000 bpd in August. Investors are also pinning their hopes on a breakthrough in peace talks during this week’s UN General Assembly.
While demand might be gradually becoming aligned with supply, this optimism could turn out to be misplaced. The unpredictability of the next 5–6 weeks will possibly ensure that there is no significant price erosion, while the loss of time value, i.e. the approaching midterms, could limit upside potential, probably keeping prices below $120/bbl.
Splendid Self-Isolation
Cooperation is more beneficial than sabre-rattling. While belligerent rhetoric and action, be it military, economic or trade warfare, might yield positive results in the immediate term, the lack of what might be coined as enlightened self-interest is harmful in the long term and could easily turn out to be counterproductive. Yes, the modus operandi of the incumbent US administration is the latest shining example of this hostile approach. It alienates former and current allies, and the narrative and actions can easily backfire. The US President prefers to endorse candidates who share his worldview and, more often than not, this helps their opponents. The case in point is last year’s Canadian and Australian elections; only a few months ago, the Hungarian strongman, an avid Trump admirer, was voted out of office after spending 16 years dismantling democratic norms.
And then there is international trade. The US approach of ‘divide et impera’ seems anything but effective. Trade barriers, tariffs imposed in the name of national security, and trade deficits not only lead to domestic inflationary pressure, which has had an explicitly adverse impact on the popularity of the Republican Party, but also force former allies to intensify bridge-building among themselves. There have been more than 10 bilateral trade agreements struck in the past 20 months, while truly multilateral deals include the EU-Mercosur agreement and the GCC-UK deal. The formula is simple. If the cost of doing business with your trading partner becomes too high, you look elsewhere. It is this consideration that has resulted in intensifying talks about Canada becoming the first ‘associate EU member’.
It is a natural consequence of the US's hostile approach to trade, seasoned with the continuous threat of annexing Canada to make it the 51st state of the United States. Canada and its Prime Minister, Mark Carney, are among the few players on the global scene who have openly refused to bow to unreasonable US demands and have consequently started seeking closer economic and even political (meaning security) ties with another partner. So, what does ‘associate membership’ actually mean?
After US-Canada trade talks broke down, the President of the European Commission was quick to support proposals for Canada to become the first ‘associate member’ of the EU. In the words of the Finnish President, ‘wouldn’t it be lovely if Canada was the 28th state of the European Union rather than the 51st state of the United States?’ The invitation, which, by the way, caught several EU members off guard, raised a few eyebrows as well as questions about the legal basis of the move; it is not direct membership, far from it. It would be more of a loose alliance, probably somewhere between the Comprehensive Economic and Trade Agreement (CETA) between Canada and the EU and full membership.
It would result in a closer trading relationship than under CETA, further lowering trade barriers. Alignment in standards across several sectors would be more conspicuous. Co-operation in defence would undoubtedly intensify, as would collaboration in research and education. The EU would also seek much closer co-operation in the areas of energy and other raw materials, such as LNG and critical minerals, with its resource-rich partner. Technological partnerships in AI, quantum computing and cybersecurity would become stronger. Although still under discussion, the movement of workers between the two partners would become easier. From a political angle, foreign policy, including security and the Arctic, would be more closely coordinated.
On the one hand, it is a bold and perhaps even revolutionary attempt, which could meaningfully shape the new world order. On the other hand, it is a logical consequence of the new geopolitical and geoeconomic realities.
The reaction from the US President was a foregone conclusion. In the same breath, he called it ‘laughable’ and a ‘hostile act’. There is a long way to go to make the plan work; nonetheless, it is an unmistakable sign of disillusionment with the US and of attempts to reduce dependence on it, which will not be a straightforward process, as Mr Trump laid it bare by threatening further economic sanctions on the EU if the invitation is maintained.
Overnight Pricing
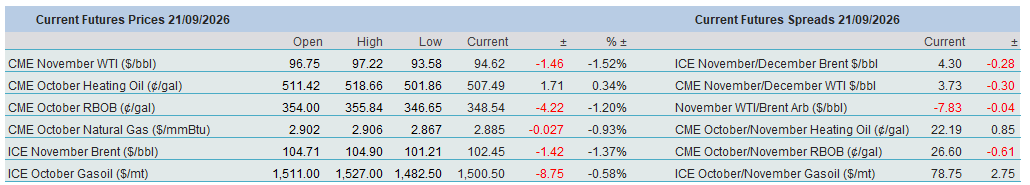
21 Sep 2026
