Tentative Peace Talks and Russian Diesel Shipments
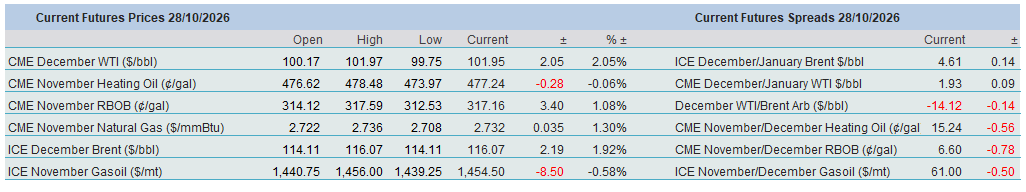
The fact that negotiations between the Mecca Alliance and Iran have not broken down and are expected to continue was sufficient to persuade sellers to emerge and push oil prices lower for the second consecutive day. Heating Oil was particularly hard-hit, with three Russian cargoes carrying 140,000 tonnes of diesel (around 1 million bbl, or less than 35,000 bpd over a month) heading towards the US as part of the White House’s deal to exempt Russian refined products from sanctions. Meanwhile, Russian refiners are increasing their runs as Ukrainian attacks have ceased and crude oil exports from Russian ports are set to decline, potentially paving the way for higher product shipments.
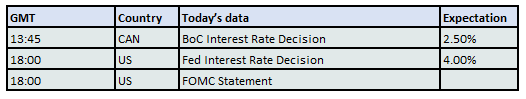
Yet it is premature to describe recent developments as a de-escalation in either region. The Houthis issued a stark reminder that further disruptions to oil refining and exports remain a clear and present danger, claiming to have attacked the Saudi Ras Tanura oil refinery. With no clear winner emerging from the Israeli election, political horse-trading is set to begin soon. A renewed joint Israeli-US attack on Iran after the US midterm elections, as suggested last week, must not be ruled out. In Ukraine, peace negotiations remain, for now, at the level of rhetoric, while strikes on Russian oil installations could resume at any time. Although attempts to broker a truce in either geopolitical hotspot are always welcome, recent events do not point to a material improvement in the global oil balance, a view the oil fraternity apparently shares. Brent jumped $2/bbl overnight despite an AI-fuelled equity rally, with the prospect of major central banks pausing rate hikes this week also providing support.
The Great Fall of China
Over the last two decades, essentially since joining the World Trade Organisation and becoming an integral part of global trade and manufacturing, China has been seen as a bulwark of economic expansion and, consequently, oil demand growth. The numbers speak for themselves. China’s economic growth regularly outpaced that of the global economy. The biggest gap was recorded just before the 2007–2008 financial crisis, when the country’s economy grew by 14% annually, compared with 5% worldwide. As its manufacturing sector expanded by leaps and bounds, Chinese oil demand increased proportionately. From 4.5 mbpd in 2000, it jumped to 17 mbpd in 2025. Just before the outbreak of the COVID-19 pandemic, China accounted for a staggering 88% of global oil demand growth.
The spectacular expansion of its economy led to the rise of the middle class, as illustrated by a variety of indicators. Its population of 1.26 billion in 2000 had grown to 1.43 billion by the beginning of the current decade. Consumer spending has fluctuated between 38% and 40% of GDP. In absolute terms, it increased 13-fold between 2000 and 2024. With its manufacturing sector expanding and consumers becoming wealthier, the domestic stock market frequently outperformed global equities. The most striking example was, once again, 2007, when the Shanghai Composite Index nearly doubled in value, dwarfing the 10% return generated by the MSCI All Country World Index.
China’s seemingly unstoppable ascent, however, appears to be coming to an end, or at least slowing, as its economic prospects fade. Population growth has stalled and even reversed slightly, forcing China to relinquish its position as the world’s most populous country to India. The result is an ageing society, a worrying decline in aggregate domestic demand, a considerable slowdown in consumer spending, a troubled property market, and combined public and private debt that has reached 300% of GDP. The lack of domestic demand makes deflation an acute headache that could develop into a chronic illness. Year to date, the Shanghai Composite Index has posted a negative return, while global equities have advanced by about 10%. Annual economic growth of more than 14% is now a distant memory, and the IMF expects the total value of goods and services produced this year to increase by a sluggish 4.5% over 2025, with growth slowing further to 4% next year.
It is difficult, and perhaps even unnecessary, to pinpoint when or where the downturn began. One could argue that it started immediately after the COVID-19 health crisis, when Chinese consumers opted to save rather than spend. Others might contend that the property crisis lies at the root of all the problems. A reasonable conclusion would be that these factors reinforce one another, with three additional ingredients contributing to the malaise. Investment in infrastructure, manufacturing and transport networks has resulted in overcapacity. A shrinking workforce weighs on aggregate demand and consumer spending, with adverse consequences for the property market, productivity and healthcare. Finally, global trade tensions also act as an impediment to Chinese growth.
Persistent deflation inevitably invites comparisons with Japan’s lost decades, when, as the Financial Times aptly observed, a property bust precipitated an economic downturn that was perpetuated by an ageing society. Stagnation and deflation characterised the Japanese economy for 20 years.
Although comparisons between the two countries may be dangerous, or even irresponsible, given the inherent differences in their political and social fabrics, the question inevitably arises: is there a way out of the current doldrums for China? Pessimists argue that the Chinese leadership is treating the symptoms rather than the underlying cause. Optimists contend that reflating the economy would be relatively straightforward if the government incentivised consumer spending. For now, however, China’s economic luminaries appear to be betting on exporting their way out of the turmoil rather than stimulating the domestic economy. As widely reported, China’s trade surplus will exceed $1.2 trillion by year-end, creating inevitable friction with its trading partners.
Time will tell whether this approach proves correct. For now, however, China is no longer supporting the global economy and oil demand growth to the extent that it did 10–20 years ago. The IEA envisages China contributing 500,000 bpd to global oil demand growth of 2 mbpd in 2027, a feeble 25%. One final, rather philosophical question is whether China’s economy, embedded in an autocratic political system, has reached its limits. At this stage, it is impossible to tell. If it has, however, China must serve as a cautionary tale for the US.
Overnight Pricing
28 Oct 2026
