A Time of Consideration
There is something of an eerie, defensive quiet reverberating around oil prices this morning. It is not that we have not been here before concerning peace initiatives, which play out on the wires rather than face-to-face, it is just that it comes with compelling and competing stories on how the Middle East has hauled itself back to producing as much oil as it did before this current war in its region began. Adding to a certain listlessness was the expiry of the November Brent contract in futures which had been the home of bullish speculation and the signpost of tightness. Without such a flamboyant yardstick, oil prices will have to be about another phase of discovery as we enter a new month and quarter.
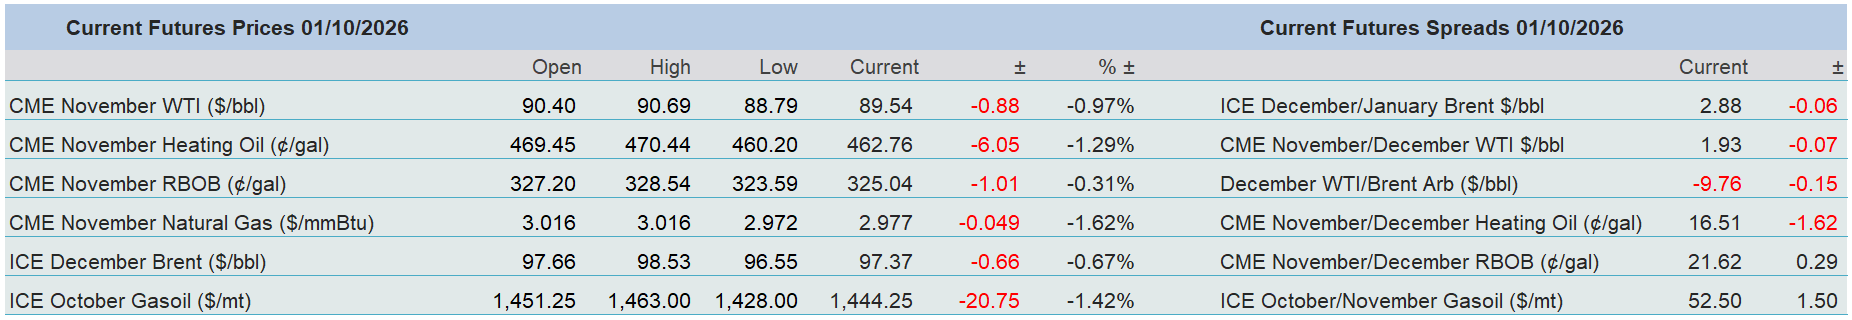
Sifting and mining for inspiration is nothing new, but the start of a new cycle gives at least a chance to be proactive, although forming an opinion that is not abandoned by a headline will likely be unchanged. Still, there does seem on the face of it a reluctance to lock missiles by the US and Iran and the clamour from Qatari mediators that at least protagonist’s ears are open to shuttle diplomacy is intriguing. The ‘Islamic Republic News Agency’ reports that Foreign Minister Araghchi presented President Pezeshkian with a US proposal after his New York trip, which included Iran’s Hormuz conditions. With the weighty voice of Goldman Sachs joining in on how Gulf nation oil exports have risen to 2025 levels the step down in futures prices this morning is justified.
Yet the product problem remains unsolved. Banning exports seems to be all the rage and while the US contemplates upsetting allies and markets alike with a diesel/heating oil restriction, China pulls no punches. This morning, as reported on ‘Reuters’, Chinese refiners have suspended exports of oil products to regions beyond Hong Kong and Macau until further notice. It would seem that this might just be a temporary consideration as Golden Week and its usual heavy consumption of fuel approaches, but taking any sort of derivative supply from the global fuel gasp will once again bring the relationship between petroleum products and their feedstocks into focus. We should all use this period of quiet contemplation well; it will not last.
Underwriting costs customers dear
The market has been forced in recent times to address the soaring cost of freight. The risk for charters in some cases is expanding as the workarounds responsible for the increasing amount of oil being supplied from the Middle East must endure quite hazardous journeys. Primarily, and as the world has found out to its worsening, the physical and geopolitical maritime chokepoints of both the Straits of Hormuz and Bab el-Mandeb lay siege to any safe passage for oil cargoes to make way to global customers. Any successful navigation is now happening in many cases by the ship-to-ship process (STS) well before the two now infamous chokepoints are crossed. Instead of one long-legged journey from Yanbu in the west or Ras Lanuf in the east of Saudi Arabia to Asia, there is now an Olympic style relay going on where oil transferred from one ship to the other before completing its race. Much of this is done in the ‘dark’, with transponders and phones turned off as marine workers try to avoid electronic detection and thereby attack. One can only imagine the threat felt by crews as they undertake these perilous practices, but insurance companies do not imagine, they can foresee disaster and are now pricing their policies accordingly.
Ordinarily, ships on the sea operate under International Navigating Limits (INL) which defines the geographical limits within which ships are able to operate without incurring additional insurance premium from hull, machinery and other insurable exposure. According to ‘Lloyds List’ INL compliance will cost large commercial ships around $976 per day or roughly $353k annually for a VLCC, although there will be caveats and surcharges if a vessel were to travel in very high latitudes or indeed skirt with conflict areas.
In July, The Joint War Committee (JWC) which draws from syndicate members from the Lloyd's Market Association and representatives from the London insurance company market, widened its “high risk” zone to include the Red Sea. Currently high or war risk zones include the Red Sea, Gulf of Aden, Persian Gulf, Gulf of Guinea and the Black Sea. These are constituted as Additional Premium (AP) Areas and when they are crossed, breached or actively traded in, the criterion for ‘INL’ no longer applies and standard insurance cover is automatically suspended while ‘AP’ or separate war-risk coverage is purchased.
To put it in context, and as seen on ‘Reuters and Al Jazeera’, insurance costs in the waterways of conflict used to constitute between 1 and 3 percent of a ship’s hull value. These have now increased to between 7.5 and 10 percent. The nature of the beast requires a bespoke hand, but analysts speculate that in some cases this can equate to $8/barrel, which is obviously not as negative a consideration as freight at present, however, it might just be the metaphorical sprinkles on this overloaded ice-cream that sends it all crashing to the floor. Shipping and insurance costs are no doubt drivers to the market speculation on how Saudi Arabia might make its crude more attractive to customers, particularly those in Asia. According to ‘Reuters’ sources, Aramco is considering offering discounts on its official selling prices (OSPs) for oil loaded off Oman to compensate buyers for record freight rates and possibly insurance.
A high price for the physical commodity is one thing, but the costings of freight and insurance are becoming a real hinderance to consumers and we are of a mind to think on a possible period of demand destruction. As suggested above, end of month and end of quarter will always come with re-evaluation, and it will be interesting to see how the next expiry cycle pans out. The incredible backwardation seen in the Brent contract across all of its mediums of trading including dated, CFDs and futures has been inspired by demand for Middle Eastern crude in Asia. Imagine then a rundown of desire in the East due to the costings of insurance and freight and then the inevitable pointing of Saudi, Iraqi and UAE crude oil tankers toward Europe. The ramifications of higher insurance on top of increased shipping rates is indeed another unforeseen development in our market that keeps us fascinated, even though our very consciousnesses are ground down by this cul-de-sac of a war.
Overnight Pricing
01 Oct 2026
