Too Little, Too Late? Possibly.
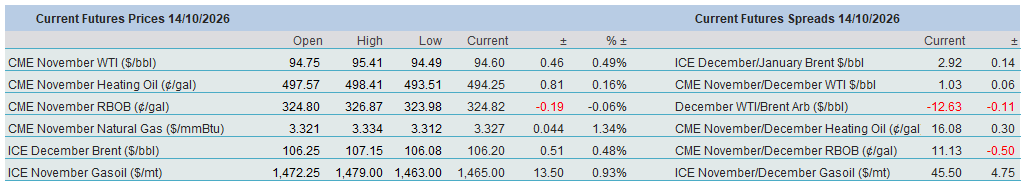
If you let your imagination run riot, you could envision a tense crisis meeting at 1600 Pennsylvania Avenue yesterday as the prices of distillates and diesel started to run amok again. The oil fraternity has seemingly concluded that the US exemption allowing Russia to resume diesel exports will make little difference in the immediate future, while what happens beyond November 3 appears irrelevant for now. The so-called ‘energy ceasefire’ has not had a chance to take effect, and it has not been adhered to. Both the CME Heating Oil and ICE Gasoil contracts rallied hard, and although they remain a fair distance from their recent peaks, their premiums to their respective crude oil benchmarks reached more than $113/bbl in the US and $90/bbl on this side of the Atlantic. According to the AAA, US diesel pump prices averaged $6.28/gallon yesterday, signalling persistent inflationary pressure less than three weeks before the midterm elections.
There was no help forthcoming from the Middle East, where the US could have a greater impact if it wanted to; after all, it is its war. Yet, escalation is the unfortunate soundbite. In the Strait of Hormuz, Iranian attacks on tankers have intensified, with 24 ships having been targeted in the last two weeks, the FT reported. On the other side of the Arabian Peninsula, the Saudi-Houthi war continues unabated. In retaliation for Houthi attacks on its airports, the Kingdom struck oil facilities in the Yemeni capital, Sanaa, while the prospect of further damage to the region’s oil infrastructure remains a disturbing possibility. Yet WTI failed to make significant headway, while Brent settled a dollar lower in what appeared to be a counterintuitive move given the strength of distillates and the escalation in the Middle East. Because of the overnight attack on Aramco’s administrative buildings in Dhahran, amends are being made this morning. 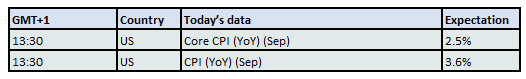
Massive Misalignment for 2027
The cynic, who knows the price of everything but the value of nothing, believes that publishing forecasts of the future oil balance as far ahead as the end of 2027 is a futile exercise. After all, even today’s and tomorrow’s events cannot be predicted with a high degree of certainty, so what is the point of forming a view of the months and years ahead? Yet the updates produced by the EIA, OPEC and the IEA month after month offer invaluable insights into what the future might hold. They naturally and understandably come with caveats. After all, no one knows how quickly the geopolitical landscape will change. However, these reports lend a helping hand by providing their audiences with a snapshot of what lies ahead. Last week, in its base-case scenario, the EIA envisaged a relatively tight balance in 4Q 2026 and a significantly looser one next year. Yesterday, it was OPEC’s turn, and today the IEA will release its latest findings.
We referred to the uncertain future above. The number of ‘known unknowns’ and ‘unknown unknowns’ is not getting any smaller. This is perfectly illustrated by the divergence of opinion among analysts. There has been, and still is, a consensus on the past. Just look at end-2025 OECD commercial inventories: the EIA puts them at 2.832 billion bbls, compared with OPEC’s 2.842 billion bbls. The figures for 1Q and 2Q are also converging. They stand at 2.798 billion bbls and 2.730 billion bbls, respectively, according to Washington, DC, and at 2.809 billion bbls and 2.741 billion bbls, respectively, according to Vienna. The chasm widens to more than 100 million bbls in 3Q and over 200 million bbls in 4Q. Why? Because the EIA sees global stocks dwindling by 1.87 mbpd and 690,000 bpd, respectively, in the second half of the year, while OPEC projects declines of 4.50 mbpd and 4.67 mbpd.
Then comes 2027. We noted last Wednesday that the EIA anticipates a 1.57 mbpd plunge in the call on DoC oil. (There is little point in comparing absolute figures, as the EIA excludes the UAE from the OPEC group, whereas OPEC has yet to remove the former member from that category.) Non-DoC and DoC production are expected to increase by a combined 8.44 mbpd in 2027. Global oil inventories will rise at an average annual rate of 4.90 mbpd, leaving OECD stocks at 3.102 billion bbls by the end of 2027, an annual build of 457 million bbls.
OPEC, on the other hand, projects growth of 1.75 mbpd in demand for oil from the extended alliance. While we assume that OPEC+ production will rise by 5 mbpd, OPEC’s estimate for non-DoC supply is considerably lower than the EIA’s—by 3.13 mbpd, to be precise. With the exception of 2Q 2027, global oil inventories are projected to draw down in every quarter of next year. The average annual draw is 1.12 mbpd. This would push OECD stocks down to 2.242 billion bbls by the end of 2027. (Full disclosure: in addition to making an assumption about DoC supply, a volatile variable, we work on the basis that 40% of global stock changes occur in OECD countries.) The gaps in the historical figures are narrowing, while those in the forecasts are widening significantly.
It is a contemporary axiom that those who accurately predict the end of the Ukrainian crisis and the timing of an enforceable truce in the Persian Gulf and the wider Middle East—one that guarantees unimpeded oil flows through the Strait of Hormuz and the Bab el-Mandeb Strait, the Suez Canal and the SUMED pipeline—will be the most successful oil investors next year. An imminent rapprochement would overturn any bullish outlook and point to a meaningfully looser oil balance. Yet OPEC’s demand outlook for 2027 is intriguing. The projected 2.6 mbpd expansion in global consumption will partly reflect the replenishment of depleted stocks. While its forecast of a yawning supply deficit may prove exaggerated, the additional demand generated by stock replenishment could mean that, even if some predictability returns to the supply side of the oil equation, this incremental demand will absorb at least part of the additional production and exports.
Overnight Pricing
14 Oct 2026
