Two Elections: Are They Critical?
As usual, last week had a lot to digest. The bond market cooled off, especially in the US. The 10-year yield fell back below 5%, retreating from the multi-decade peak of 5.365% registered at the beginning of October. The retreat, however, did not reflect improved inflation expectations. Judging by the relentless increase in oil prices, inflation will accelerate further. The reason for the correction was that Treasury bonds fulfilled their classic role as a safe haven when equity markets sent out ominous signals, as was the case last week. The Nasdaq Composite Index lost 0.71% over the week, as anxiety about the AI sector intensified amid growing concerns about what is increasingly seen as the reckless need for the sector’s leading companies to raise cash. Simply put, there is a rising certainty that revenues will not be sufficient to service their debt. And it was not just the US tech sector that took a hit: the South Korean stock market, led by chipmakers, registered its fourth consecutive weekly loss, while in Japan, the Nikkei 225 Index posted a weekly loss of 4%.
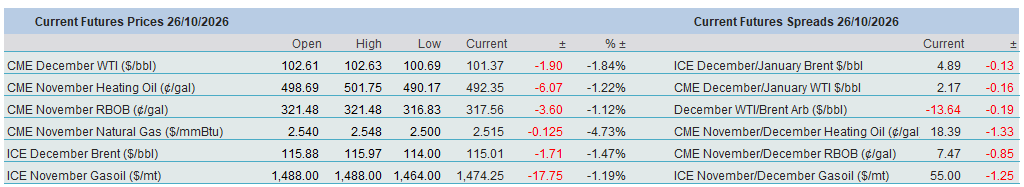
All the while, global inflationary pressures will not subside. Energy prices directly affect headline inflation and indirectly influence the core reading. After weekly gains of 4.29% in WTI, 6.24% in Brent, and 5.59% in Gasoil, it is obvious that consumer price inflation will remain elevated and that central banks will not be given the luxury of keeping interest rates at current levels for long, let alone cutting them. High borrowing costs are an unmistakable sign of demand destruction. Yet, Brent’s ascent to a six-month high last week suggests that supply, output and export considerations remain the dominant immediate drivers, notwithstanding renewed weekend attempts by Qatar and the Mecca countries to re-ignite peace talks with Iran, which have resulted in some profit-taking as the new week kicks off.
But why are oil traders so concerned about the availability of oil? After all, Russia, the US and China are making genuine efforts to bring the Ukrainian conflict to an end, while several market watchers put Middle Eastern crude oil exports above pre-conflict levels. To begin with Eastern Europe, even though the weekend temporary ceasefire around the occupied Ukrainian town of Oleshky, brokered by the Pope and the US First Lady, is an unreservedly welcome step, doubts about any breakthrough in the tentative Ukrainian peace talks hardly need elaboration. While talks on a technical level between the US, Russia and Ukraine could be held next month, the planned trilateral negotiations might, if they take place at all, involve only the US, Russia and China. We are talking about a conflict in which one of the parties is not only being kept in the dark about what is on the menu but is not even being offered a place at the table. Déjà vu is the appropriate soundbite here, however historic the circumstances, and one cannot help but draw parallels with the 1945 Yalta Conference, where the US, the UK and the Soviet Union divided the world into spheres of influence. The Russians, relying on the not-so-tacit support of the US, know they are in no hurry to conclude the war, while Ukraine will go to great lengths to avoid caving in to unreasonable and unacceptable Russian territorial and political demands. The war will plausibly continue, with all the repercussions this entails for the global oil balance.
Last week’s oil price rally came despite rising exports from the Middle East. According to Kpler, the analytics and data company, shipments from Persian Gulf producers reached 24.6 mbpd in the week ending October 18, as reported by the Financial Times. Investment bank Morgan Stanley estimated that crude oil exports alone had recently risen to 17 mbpd from the region.
Yet tensions in both the Strait of Hormuz and the Red Sea made it impossible for investors to adopt a bearish view. Frequent attacks on tankers navigating these critical waterways have reached a record high in October, and will undoubtedly hurt export volumes in the near future and keep freight rates sky-high. In western Saudi Arabia, the Iran-backed Houthi rebels have been waging a disturbingly effective campaign against the Kingdom, jeopardising the safe movement of oil along alternative routes. Over the weekend, oil pumping stations and the Riyadh airport were reportedly attacked. Lastly, maintaining elevated regional export volumes, partly through practices such as ship-to-ship transfers, comes at an unsustainably high cost.
Against this backdrop, two seemingly pivotal and consequential elections are about to take place. Tomorrow, Israeli voters will decide who will form the next government in the Jewish state. Polls put the incumbent, Benjamin Netanyahu, on a par with Gadi Eisenkot, the former head of the Israel Defence Forces. Whatever the outcome, neither side will be able to command an outright majority in the 120-seat Knesset. Political horse-trading will begin after the election, which was preceded by a campaign during which no candidates ran on a two-state agenda. There will be no tangible relief for the Palestinians.
A week later, Americans will vote to determine which party will control Congress. While the House of Representatives will most likely return to Democratic control, the Senate, currently held by the Republicans, could go either way. Should the Republicans lose it as well, they will have only Donald Trump to blame. The President’s approval rating is at a record low, possibly for two related reasons. His ill-fated import tariffs, coupled with the unnecessary war in the Middle East, have triggered what has become known as the ‘affordability crisis’. When the pocket of the US consumer is picked, the consequences might and should be severe.
Until very recently, there was a strong case for concluding that, once these elections were out of the way, the end of the Middle East acrimony would be within reach, potentially following the formation of a new government in Israel and a Democratic clean sweep in the US. The latest reports by The New York Times, however, suggest that a ‘short but intensive’ operation against Iran will take place soon. Mike Waltz, the US ambassador to the UN, said in an interview with the Financial Times that the conflict in the Middle East could drag on for another year, if not longer. Hopefully, that will not be the case. But if it is, all projections of a looser oil balance will need to be revised, and the only point of contention will be when demand destruction, driven by persistently high energy prices and inflationary pressures, will replace supply considerations as the salient factor in the formation of oil prices.
Overnight Pricing
26 Oct 2026
