Unbelievable
When you cannot keep the bedroom out of the boardroom it is still amazing how much damage the bassist of human instincts might wreak. While the board of Nvidia weigh the future of CEO and co-founder, Jensen Huang, his extramarital affair has brought the former darling of tech to a reputational crisis so deep that it has accelerated losses of the company’s share price, which initially started from the A.I. scrutiny in October, to nearly $1.5 trillion in market value. Such moves of consequence cannot fail to influence the behaviour of investors, not only in Nvidia, but to all companies that it has invested in and who are likewise invested in reverse, outlining the danger of this circular relationship of ‘frenemies’.
Bringing an Nvidia influence back to our market is something of stretch until the farrago is sorted out, but uncertainty now plagues the biggest market movers of the year, namely A.I. and of course the Iranian war. There is a ground shake, and confidence is low because the headlines and words of both leaders of company’s and countries alike are fraught with simple untruths or omissions. There is now a campaign that stretches across every trading and investment suite, and their communities ranging from risk initiators to analysts, to syphon that which is fact and that which is fiction. Good luck to us all.

The great wall of silence
There has been an audible silence from China over the 9-months of this cul-de-sac of Middle Eastern war. One might assume Beijing would be much more vociferous in its protest in how its reliance on Gulf State crudes is forcing it to change its import habits of feedstock. This is particularly true of the trading relationship it has with Tehran. Total numbers vary a touch, but through 2025, and in fact the years that preceded it, between 80 and 90 precent of Iran’s crude oil exports found destinations in China. According to such weighty sources as the US-China Economic and Security Review Commission, in 2025 China imported almost 1.4 million bpd of Iranian oil, which accounted for about 12 percent of its total crude imports, enjoying steep discounts of between $8 and $10/barrel. This favoured custom is in monetary terms no mean amount, and it is curious as to why China refrains from calling ‘foul’ and bringing more gripe to the United States, the initiator of this war.
It is not just the crude from Iran being stymied as a supply source, China draws from a spectrum of Gulf States, therefore the problems of Hormuz have caused it to make radical changes in its oil trading behaviour. There are no official data on how large or the changes that might have been made to its vast strategic reserve, but because it has no commitments to the wider OECD consideration and has for some years looked only to its own interest, China has not been compelled to join in with strategic releases, as coordinated by the IEA which in many ways helped stem crude prices from running away into deep three-figure territory. The United States, as part of the IEA 400-million-barrel initiative, is well on the way to releasing a promised 172-million-barrel contribution taking its SPR to 282.2 million barrels in the week ending October 30th, the lowest level since October 1982.
Instead, Beijing put in action a spate of self-control or a form of rationing if you like. Slashing crude oil purchases between 20 and 30 percent in the months after the February start to the war, and in March suspending new export licenses for gasoline, diesel and jet fuel, and, according to the Centre of Research on Energy and Cleaner Air, allowing the lower fuel exports to offset nearly 29 percent of the drop in domestic refinery output. Last year, and until February, China was loading its SPR to the tune of 1.1mbpd so says the US EIA. Such a surplus became unavailable but again is an offset, and because, according to many opinions, including Bloomberg, the net 1mbpd draw on crude stocks which eventually came about was serviced by commercial holdings rather than SPR. China’s most prized energy security asset has been largely untouched, although it is impossible to be certain that it has not been utilised in some way.
Russia has helped fill any import gap. The Moscow/Beijing relationship of convenience has seen the northerly partner increase its crude exports to the globe’s largest importer by 18 percent and now accounts for nearly a quarter of all Chinese oil imports. Beijing will do business with all, be they sanctioned or nay. But oil market astuteness and geopolitical skills including a willingness to go chest-to-chest with the United States if it flexes its trading muscles has allowed a decent navigation of what might have been potentially a major economic disrupter in a country so reliant on oil imports. Making a stand over Iran and siding with Tehran is not in China’s favour. It has broader economic priorities with the United States and Europe, but also whatever investments it might have in Iran, they do not tip any scale when measured with the growing relationship being nurtured with the more important markets of Saudi Arabia and the UAE. Being drawn into defensive entanglement of Iran will alienate its delicate foreign policies. By doing the opposite, China will portray an aura of restraint, of diplomatic prowess and when the US finally leaves a vacuum in the theatre of the Gulf, the backstage role of Beijing as mediator and reliable ally will garner great rewards. Staying quiet over Iran is expedient in so many ways, unless of course, this unwanted war takes an ill turn, and the world’s ‘swing consumer’ starts to gasp in oil thirst.
Overnight Pricing
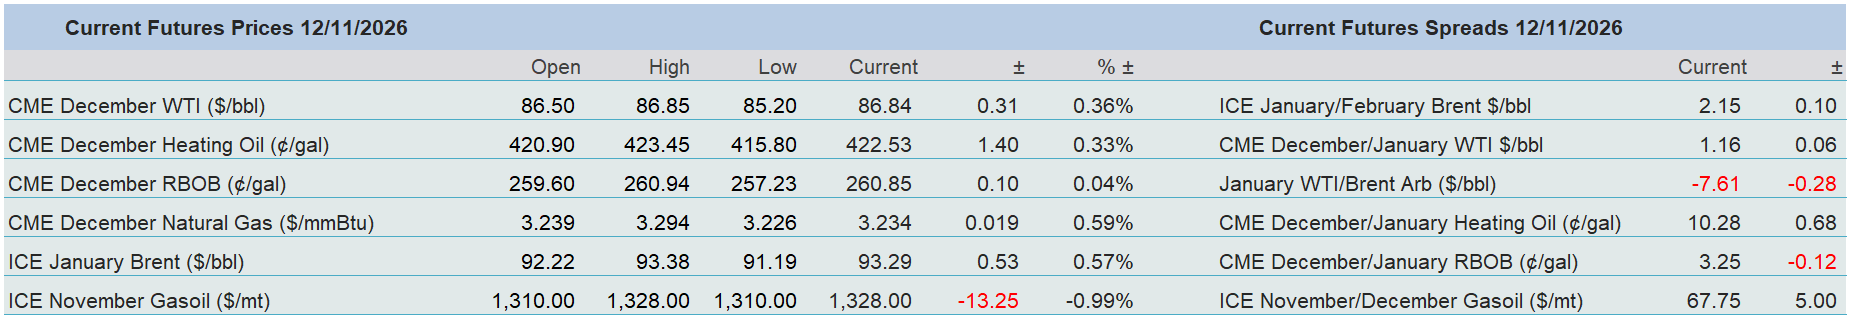
12 Nov 2026
