Uncertain Truce, Uncertain Diesel, Undisputed Inflation
Predicting price movements is a brave undertaking. Betting on de-escalation, either in the Middle East or Ukraine, ditto. Tension undeniably keeps brewing, and not exactly under the surface.
Although Saudi Arabia is pumping oil through the East-West pipeline after the latest hiatus, loading at Yanbu has not started yet. Moreover, the Kingdom has been forced to intercept Houthi missiles targeting the aforementioned export hub in the Red Sea. This is not the recipe for a thaw.
Confusion surrounding the diesel market persists. The intraday rally of $12/bbl equivalent in the CME front-month contract suggested that the US Administration would shelve its plan to ban exports of this critical agricultural fuel. Yet, towards the end of business last night, the contract was pushed over the precipice and dropped $14/bbl equivalent within three hours after the US energy secretary reportedly sought support from US refiners for voluntary restrictions on exports. All the while, Brent, the most sensitive to Middle East developments, rallied by over $3/bbl amid stalled, or perhaps even non-existent, talks between the US and Iran, although headlines implied that the current phase of negotiations is concentrating on a staggered reopening of the Strait of Hormuz. This parley has led to rising optimism about a possible armistice once again, and oil prices, also pressured by Heating Oil, are retreating from yesterday's general bounce.
Only losers emerge from this conflict, and not just the adversaries directly involved; the global economy collectively suffers. The US is no exception. As inflationary pressure mounts, bond yields are on the rise. It now costs the US Treasury 4.9% per annum to borrow for two years and 5.17%—the highest since 2007—for 10 years. Homeowners with mortgages are compelled to cough up more than 7% on top of the principal repayment. Whilst the phrase ‘affordability crisis’ is largely banned amongst public servants, what is happening to US diesel prices and mortgage rates is, in fact, the very definition of an ‘affordability crisis’.
No doubt, this madness will come to an end; that much one can be confident of. Even the timing of it is becoming clearer—possibly after November. Worryingly, though, the outcome and what will happen in the interim are not.
Solid Economic Outlook with Strings Attached
Oil and equities used to go hand in hand. Rising stock markets implied robust economic activity, which supported global oil consumption. OPEC used to do the rest by raising or cutting output to balance the market. This connection has been upended for much of the current year. It has become a daily phenomenon to see the price of a barrel move in one direction while equities move in the other. The reason for this misalignment is the geopolitical conflicts investors have to deal with on a daily basis. Oil is presently being driven by supply considerations. An oil price rally, precipitated by output or export destruction, implies rising inflationary pressure and higher interest rates, which impede economic growth, and vice versa. The capricious nature of the ongoing wars leads to headline-driven trading and a consequent rise in volatility. Added to this unpredictable backdrop is the emergence of the AI sector at frightening speed, which promises to increase productivity, helping economic growth, or to trigger a global Armageddon, destroying the entire planet. Judging by the relentless climb of the tech-heavy Nasdaq Index, investors are betting on the former.
The collective economic impact of the Ukrainian crisis and the Middle East conflict is all too obvious to see. No major economy is anywhere near its declared 2% inflation target, as consumer and producer prices, both headline and core, are on the ascent, forcing monetary policymakers to raise the cost of borrowing. The latest examples are the Federal Reserve and the Bank of Japan. These are ominous signs and bleak prospects for healthy economic expansion. Yet, the latest interim report of the OECD Economic Outlook, while not unreservedly upbeat, is cautiously optimistic.
The update acknowledges the headwinds the world has had to deal with in the face of perpetual adversity. Yet, it concludes that despite moderating global growth in the first half of 2026, the economy as a whole remained resilient in several countries and has been weathering the storm impressively. The effective use of strategic and commercial oil stockpiles, discretionary government support measures, and AI-related activity have all helped mitigate the negative impact of expensive energy.
Looking forward, the picture is tentatively reassuring. The global economy is expected to expand at a rate of 2.9% for the whole of 2026 and 3% in 2027. These estimates are unchanged from the June 2026 forecast; however, the OECD points out that the commodity price shock, if it persists, will strain inventory usage and household spending.
Growth in the G20 economies is expected to remain stable. The US is anticipated to do particularly well, partly due to the expansion of AI investment. The US economy is seen growing by 2.2% this year and 2.1% next year. The euro zone is lagging and will continue to lag. In 2026 and 2027, its growth rate is expected to remain at 1%, as high energy prices and policy rates weigh on its economy. In the Far East, Japan will experience strong business investment, the positive impact of which will be offset by higher interest rates. In South Korea, this year's 3.7% growth, driven by strong industrial production, will retreat to 2.6% in 2027 as private consumption moderates. And finally, China. Although its economy is expected to expand by 4.5% this year and 4.2% next year, below the 5% recorded in 2025, it will remain the major contributor to global economic expansion. One cannot help but conclude that countries relatively far from the current conflict zones are expected to perform better than their peers closer to the firing line.
While these are semi-decent projections that do not envisage a recession, these days every prognosis comes with a risk disclosure. Growth rates can be affected by persistent constraints on exports via the pivotal chokepoints around the Persian Gulf or sustained damage to the region's energy infrastructure. Additionally, fiscal challenges, higher borrowing costs, and growing piles of public debt can also act as a brake on growth. In the absence of such negative developments, energy prices are expected to decline in 2027, helping to tame inflationary pressure and support economic—and therefore oil demand—growth. A realistic scenario? Do not hold your breath.
Overnight Pricing
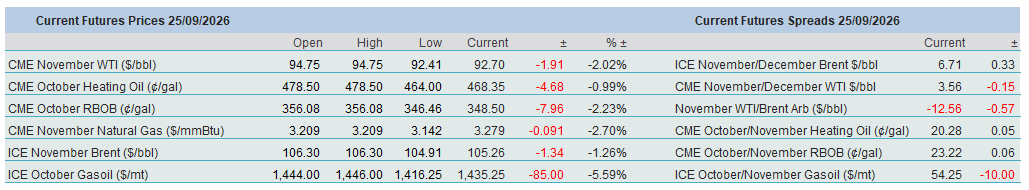
25 Sep 2026
