Whirlwind Trading Conditions
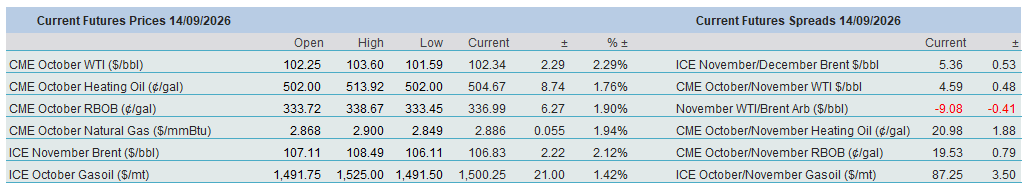
There was nothing unique about last week’s market performance, which saw oil settle higher, equities lower, and bond yields jump. All that happened was that the Iranian conflict unexpectedly escalated. De-escalation is a daydream. The weekly move higher in oil prices is therefore justifiable, as was the Friday correction, when reports emerged of talks between Gulf nations and Iran aimed at reaching an interim deal that might open the Strait of Hormuz, providing an unmissable excuse to cash in on some length. Needless to say, the meeting has been postponed. Worse yet, Iranian attacks in the Gulf and Houthi aggression in the Red Sea continue. The latter forced Saudi Arabia to temporarily shut its critical East-West pipeline. In the absence of any breakthrough, the downside is limited, and oil stocks, which the IEA now expects to fall faster than previously thought, will not be replenished any time soon.
The collateral damage from the Gulf crisis is higher consumer prices and rising bond yields. US August headline CPI rose slightly, while the core reading edged lower. A Fed rate hike would be warranted this week. Will it happen? It is hard to determine, as US monetary policy is highly politicised. As said above, it is business as usual. Nonetheless, two related developments stood out from last week’s smorgasbord of events. First, President Trump believes that Iran will not end the war until after the midterm elections. Second, he shamelessly, and perhaps nefariously, offered $5,000 to every adult American should the Republicans remain in control of the legislature after November. It is a tacit admission of the plunging popularity of his party and the common denominator with his view of Iran’s approach to the conflict. The hasty conclusion is that the Persian Gulf El Dorado will only arrive once the midterms are in the rear-view mirror. Until then, logic dictates, there will be no relief.
What can stop the grind higher?
We must admit to being a little too enthusiastic in bullish calls when the Strait of Hormuz was first subject to being the barter point of the Israel/US and Iran war. Intrepid shippers who found alternative routes to customers and the very quickly deployed strategic petroleum reserve release orchestrated by the IEA left us, and we were not alone, with a little egg on the face as we contemplated $120/barrel Brent. But the consideration is once again live, and the upward pressure in prices that seems to intensify on a daily basis does not at present appear to have the cures this time around as was seen during May and June.
For one thing, the Saudi cheat of Hormuz, in which the Kingdom shifted greater volumes of crude to its western shore of the Red Sea via Yanbu to service its contracts with the likes of China and other Asian destinations looks to be a busted flush. One of the last active and successful proxies of Iran, the Houthi rebels of Yemen, have had inordinate success in hampering Saudi and other shipping in negotiation the Bab al-Mandab Strait, linking the Red Sea to the Gulf of Aden where oil stuffs might flow into the Indian Ocean to Far East ports. Emboldened, and with a spiralling situation between the US and Iran as they attempt to sink each other’s or their allies’ tankers, Houthis are now attacking the south-west towns and cities of Saudi which service the oil facilities of Jazan and by doing so, halt refinery activity.
Staying with the global refining issue, and diverting away from the Middle East, the dogged resistance of Ukraine and its mastering of drone warfare have, as of the beginning of August, brought Russian capacity to its knees. Refineries processed an estimated 3.6 million barrels of crude per day, the lowest level since May 2002, according to EA Analytics data cited by ‘Bloomberg’, roughly one-third below the seasonal norm. ‘Bloomberg’ go on to compare how processing averaged between 5.3 million and 5.6mbpd during the same period of the year between 2020 and 2025. In the US, and at the end of August, the total refinery utilisation rate across the U.S. was 98 percent which is all but deemed full capacity and has run above 95 percent for three consecutive months, the longest since 2000. Such gangbusting throughput is seen in the thirsty sub-continent. As revealed via ‘Reuters’, India’s refinery capacity utilisation has been 105 to 108 percent over the last 6 months as product tightness is felt everywhere. There is still a worldwide scramble for finished fuels with shortages in fuel oil for ships and even reports of a possible brewing in issues for jet fuel as refiners prioritise the production of diesel. Given the refineries enclosed by Hormuz, the damages sustained by Russian refineries and the up and until now Chinese export quota cuts, several sources presume global refinery capacity is offline to the tune of 8mbpd.
Reverting to the solutions which spurned previous calls for higher crude prices, there will be no further cavalry charge of rescue coming from inventory releases as has been seen. Much of the heavy lifting of releasing crude reserves was undertaken by the United States. The current administration in the White House committed 172mb as part of the coordinated 400mb, 32-member nations IEA release. However, despite promises to the contrary, President Trump had not been able to refill the drain seen during a similar release seen in the Biden presidency against the price shocks of the Ukraine war. According to ‘S&P Global’, the US Department of Energy said, when the release was announced on 11th of March this year, it would take roughly 120 days to deliver. Not only is the US SPR now closing in on the lowest it has ever been at 270.5mb in 1982, the caverns in which it is stored are near operational lows, the point in which their geology becomes compromised.
Even if price precludes China from its usual buying prowess, its thirst will not entirely stop the fuel-hungry nation from activity. Having drawn down on reserves, and offering a subjective view that it would rather be energy rich and a little poorer, it does seem unlikely that the low import level of 7.5mbpd seen in June will be repeated, which is still a significant demand number. The fixes of finding alternative means of delivery and ability to quench global demand with SPR are now starting to run their course. Short of stopping both oil price affecting wars and curing the global refinery problem, our fraternity is wondering where an inoculation against $120 Brent can be found.
Overnight Pricing
14 Sep 2026
